Category: BLOG

  • Using a Virtual Card With Apple Pay and Google Pay

    Using a Virtual Card With Apple Pay and Google Pay

    Example scenario: you buy a virtual card for online subscriptions and notice it could also pay at the coffee shop if it were in your phone wallet. You open Apple Wallet, type in the number, and get “Card Not Supported”. Your friend adds a different virtual card to Google Wallet in under a minute. Same phone type, same kind of card, different result.

    Using a virtual card with Apple Pay or Google Pay is common, and when it works it turns an online-only card into one you can tap in stores. Whether it works depends on decisions made by the card issuer and the wallet, not on you. This guide explains how wallet provisioning works, walks through the steps for both wallets, and covers the reasons a card gets refused.

    How adding a card to a wallet works

    When you add a card to Apple Pay or Google Pay, the wallet does not simply store your card number. It asks the card network and the issuer to create a separate device token, a stand-in number tied to your phone or watch. When you tap or pay in an app, the merchant receives that token instead of your real card number.

    That process involves three parties, and any one of them can say no:

    • The wallet must be available in your country or region, on your device.
    • The card network (Visa, Mastercard and so on) must support tokenization for that card.
    • The issuer (the bank or institution behind the card) must take part in that wallet and approve this specific card. Issuers often verify you with a code by text, email or app before activating the token.

    Apple’s own support pages note that some cards from participating banks may not be supported, which tells you approval happens card by card, not bank by bank.

    Where it works and where it doesn’t

    FactorUsually works whenOften fails when
    Wallet countryThe wallet supports payments in your country or regionThe wallet is not available where you live
    Issuer participationThe issuer takes part in that walletThe issuer has not enabled the wallet, or not for this card type
    Card typeThe issuer allows the card type (some allow prepaid, some do not)The issuer excludes prepaid or virtual cards from wallets
    VerificationYou can receive the issuer’s code or confirm in its appThe issuer cannot reach you or the details do not match
    MerchantThe store takes contactless or the site offers Apple Pay or Google PayThe merchant does not offer the wallet at checkout

    Apple publishes Apple’s list of countries and regions that support Apple Pay, and Google has Google’s supported countries page for Google Wallet, with features such as tap to pay listed by country. Check both before you assume a card will work.

    How to add a virtual card to Apple Pay

    1. Open the Wallet app on your iPhone and tap the plus button.
    2. Choose to add a debit or credit card. Prepaid cards are added through the same option.
    3. Enter the card details manually: card number, expiry date, security code and the cardholder name. Use the details exactly as shown by the provider.
    4. Accept the issuer’s terms if asked. These come from the card issuer, not Apple.
    5. Complete verification by entering the code the issuer sends, or follow its instructions.
    6. Test it with a small contactless purchase or an online checkout that offers Apple Pay.

    To use the card on an Apple Watch, add it again through the Watch app. Each device gets its own token.

    How to add a virtual card to Google Pay

    1. Open Google Wallet on your Android phone and tap “Add to Wallet”.
    2. Choose payment card, then new credit or debit card.
    3. Enter the card details manually: number, expiry, security code and billing address.
    4. Accept the issuer’s terms and complete verification.
    5. Set up a screen lock if prompted. Google Wallet requires one for tap to pay.
    6. Test it with a small payment in a store or app.

    Menu labels change between app versions, so look for the closest match if yours differs.

    Troubleshooting common errors

    “Card not supported” or “This card can’t be added”

    The issuer has not enabled this card for the wallet, or not in your country. Nothing on your side fixes this. Ask the provider whether the card supports that wallet.

    “Contact your card issuer”

    Provisioning started but the issuer did not approve it automatically. The issuer may need to verify you. Contact the provider’s support with the error message.

    Verification code never arrives

    Check that the contact details the provider holds are current, then try again later. Repeated attempts in a short time can trigger extra checks.

    Card added but payment declined

    Check the balance, the card’s freeze status and whether the merchant accepts that network. A prepaid card with too little balance is declined like any other card.

    Should I change my phone’s region to make it work?

    No. Changing device region to force a wallet can break other services and may go against the wallet’s terms. If the wallet or issuer does not support your country, use the card online instead.

    Is a wallet safer than typing the card number?

    In most cases, yes. The merchant receives a device token rather than your card number, and each payment is confirmed with Face ID, Touch ID, fingerprint or passcode. If your phone is lost, you can remove cards remotely. The underlying card still matters: if the card itself is compromised online, freeze it with the provider.

    Example: Vizovcc cards in a phone wallet

    Vizovcc sells prepaid virtual cards and its card pages show Apple Pay and Google Pay compatibility. That makes it a useful example of how this works in practice, and of the limits.

    You fund a Vizovcc balance with crypto, buy a card, and the number, expiry and security code appear in the dashboard once the card is ready, often within minutes. From there, you add the card to Apple Wallet or Google Wallet using the manual steps above. You can read more about its prepaid Visa and Mastercard cards on the Vizovcc site.

    The honest caveat applies here as it does to every provider: whether any card can be added to a wallet depends on the card issuer and on the wallet’s rules in your country. A card page showing wallet compatibility tells you the card type has supported wallets, not that every phone in every country will accept it. Before you buy:

    • Check the specific card page for its wallet notes and currency.
    • Confirm Apple Pay or Google Pay works in your country using the official lists.
    • Remember that card purchases are final, so make sure the card fits your use before buying.
    • Keep enough balance for the purchase, since the card is prepaid and cannot go below zero.

    Other Vizovcc features carry over to wallet use: you can freeze and unfreeze a card from the dashboard, cards support 3D Secure for online checkouts, and you can hold several cards from one balance. Funding is crypto only, and any merchant can still decline a prepaid card.

    FAQ

    Can prepaid virtual cards be added to Apple Pay?

    Many can, if the issuer allows prepaid cards in Apple Pay and Apple Pay is available in your country. Some issuers exclude prepaid cards.

    Does Google Pay work with virtual cards?

    Yes, when the issuer supports Google Wallet for that card and tap to pay is available in your country. Online payments in apps and websites have their own country list.

    Do I need the physical card to add a card to a wallet?

    No. You enter the number manually, which is how virtual cards are added.

    Key takeaways

    • Wallets create a device token for your card, and the issuer must approve each card.
    • Wallet country, issuer participation and card type decide whether a card can be added.
    • “Card not supported” is an issuer or country decision, not something you can fix on your phone.
    • Check the official country lists and the card page before buying a card for wallet use.
    • Wallet payments hide your card number from merchants, which is a security plus.

    Before you buy any virtual card for tap-to-pay, check the wallet’s country list and the card’s own page. If you want a prepaid card whose pages list Apple Pay and Google Pay compatibility, take a look at Vizovcc and confirm the details for your country first.

  • Crypto Virtual Cards: How They Work and What They Cost

    Crypto Virtual Cards: How They Work and What They Cost

    Here is a situation many freelancers paid in stablecoins know well. A developer receives her monthly fee in USDT. Her design tools, hosting and AI subscriptions all want a card. Moving the USDT to an exchange, selling it, withdrawing to her bank and waiting for the transfer takes days and costs fees at every step. By the time the money reaches her card, a renewal has already failed.

    A crypto virtual card shortens that path: you send crypto, it becomes spendable card balance, and you pay online with a normal card number. The idea is simple, but the costs and risks sit in places most people don’t look. This guide explains how the top-up flow works, every fee you can meet along the way, the tax and compliance points, and who these cards suit.

    Two models behind “crypto cards”

    Products sold as crypto cards usually follow one of two designs:

    • Convert at payment. You keep crypto in an account, and each card payment sells just enough at the moment you pay. Your balance stays in crypto until you spend.
    • Convert at top-up. You send crypto to the provider, it is credited as a balance in a fiat currency such as US dollars, and the card spends that balance. Your exposure to crypto prices ends when the deposit is credited.

    Convert-at-payment suits people who want to stay invested until the last second. Convert-at-top-up suits people who want a predictable dollar amount for bills. Most prepaid virtual card platforms use the second model.

    How a top-up works, step by step

    1. Choose a coin and network. USDT, for example, exists on several blockchains. The provider accepts only specific ones.
    2. Get the deposit details. The provider shows an address and an exact amount, often with a time limit on the quoted price.
    3. Send from your wallet or exchange. You pay the network fee. If an exchange deducts its withdrawal fee from the amount, less arrives than you entered.
    4. Wait for confirmation. The transfer is confirmed on the blockchain, then checked by the provider.
    5. Balance credited. The deposit becomes spendable balance, often in US dollars.
    6. Buy or fund a card. You use the balance for a virtual card and enter its details at the merchant.

    The mistake that can’t be undone

    Sending on the wrong network is the most expensive error. If a provider accepts USDT on TRON (TRC-20) and you send it on Ethereum or BNB Smart Chain, the funds may never be credited, because blockchain transfers can’t be reversed. Always match both the coin and the network shown on the deposit page, and send a small test amount first if the provider allows it.

    Every cost you might pay

    A crypto virtual card can be cheap or expensive depending on how many of these layers apply:

    Cost layerWho charges itHow to keep it low
    Buying the cryptoExchange or on-ramp spread and trading feeSkip this layer if you already earn or hold crypto
    Withdrawal feeYour exchange, when sending outCompare networks; fees vary widely by chain
    Network feeThe blockchain (paid to validators or burned)Low-fee networks such as TRON or Solana usually cost less than Bitcoin
    Conversion spread or top-up feeThe card providerCheck that the provider shows its rate or fee before you send
    Card feesThe card provider: issue, monthly and per-payment feesPrefer one-time fees over monthly fees if you hold several cards
    Foreign exchangeCard issuer, if the card’s currency differs from the merchant’sUse a card in the currency the merchant bills in
    Price movementThe market, for volatile coins between sending and creditingUse stablecoins, and send before a quoted price expires

    Stablecoins versus volatile coins

    USDT is designed to stay close to one US dollar, which makes it the natural choice for paying bills. Bitcoin and SOL can move in the minutes or hours between sending and crediting, and Bitcoin usually takes longer to confirm. If the amount matters, fund with a stablecoin and keep volatile coins for holding.

    Tax and compliance: what doesn’t change

    Spending crypto is usually a taxable event, even when it feels like moving money between your own pockets. In the US, the IRS’s FAQ on digital asset transactions states that digital assets are treated as property, and that paying for services with them is a disposal that can produce a capital gain or loss. Converting crypto into card balance can count the same way. Other countries have their own rules, so keep a record of each deposit’s date, amount and value, and check with a tax adviser where you live.

    Crypto funding also doesn’t make a card anonymous. Reputable providers may ask for identity verification, screen against sanctions lists and refuse cards from sanctioned countries. A crypto-funded card is a payment tool, not a way around KYC, tax, platform rules or currency controls.

    Who crypto virtual cards suit, and who they don’t

    Good fitPoor fit
    Freelancers and remote workers paid in stablecoinsPeople who would buy crypto only to fund the card, paying spreads twice
    Online businesses that hold crypto revenue and pay for software or adsAnyone who needs credit, rewards or strong chargeback rights
    People whose local cards fail on foreign merchantsPeople who want to avoid identity checks or tax reporting
    Teams that want separate prepaid cards per vendor from one balanceUsers who need in-person payments with a physical card

    A checklist before you choose a provider

    1. Which coins and networks are accepted, and what happens if you use the wrong one?
    2. Is the conversion rate or top-up fee shown before you send?
    3. How long does a quoted price hold?
    4. Which card networks and currencies are available?
    5. What are the issue, monthly and per-payment fees?
    6. Can you withdraw unused balance, in what form, and at what cost?
    7. What happens to your money if a card can’t be issued?
    8. Which identity checks apply, and when?

    Worked example: a USDT-funded card on ZenVCC

    ZenVCC follows the convert-at-top-up model. It is a prepaid virtual card platform, not a bank, and it answers most of the checklist above on its own pages. ZenVCC’s guide to USDT-funded cards walks through the deposit flow in detail.

    • Coins and networks: Bitcoin, TRX, SOL and USDT on TRC-20 or Solana. USDT on other networks, such as ERC-20 or BEP-20, is not accepted, and a wrong-network transfer can’t be credited or recovered.
    • Deposit flow: the deposit page shows an exact amount and address. You send the full amount in one payment before the quoted price expires, then submit the transaction hash. Each deposit is checked on its blockchain before your balance is credited in US dollars.
    • Fees: you pay your wallet’s network fee, and any payment-method charge is shown before you pay. Each card costs its price plus a one-time $10 issue fee, each card payment costs $0.10, and there is no monthly fee.
    • Cards: about 50 cards across Visa, Mastercard, American Express, Maestro and some UnionPay and JCB options, including USD and local-currency cards. Cards are valid for three years.
    • Refunds and withdrawals: if a card can’t be prepared, the full amount, issue fee included, returns to your balance. Unused balance can be withdrawn in crypto, with a $10 minimum and no withdrawal fee, after a review. Money on a card can’t be moved back to the balance.
    • Identity: ZenVCC may ask you to verify your identity before you buy a card, whichever coin you use.

    There are limits to plan around. Cards can’t be topped up from the dashboard, there are no in-app spend limits or card freezing, and a payment that asks for a 3-D Secure code can’t be completed, because the dashboard doesn’t show those codes. Each platform also decides which cards it accepts, so test a new card with a small payment first.

    Key takeaways

    • Most crypto virtual cards convert your crypto at top-up into a dollar balance, then spend it like any prepaid card.
    • Costs stack in layers: exchange, network, provider and card fees, plus exchange rates and price movement.
    • Match the coin and network exactly. Wrong-network transfers usually can’t be recovered.
    • Stablecoins keep the amount predictable for bills.
    • Spending crypto can be taxable, and identity checks still apply.

    Before your next top-up, run through the checklist and add up every cost layer that applies to you. If a prepaid card funded with USDT, Bitcoin, TRX or SOL fits the way you earn and spend, take a look at ZenVCC and compare its fees with your current route from crypto to card.

  • TikTok Ads Billing Explained for New Advertisers: Manual vs Automatic Payment

    TikTok Ads Billing Explained for New Advertisers: Manual vs Automatic Payment

    Your first TikTok campaign was approved, spent for a few hours, and then stopped. Ads Manager shows a payment warning or a zero balance, and you can’t tell whether you picked the wrong billing mode, the wrong card, or both.

    Quick answer

    1. Manual payment: you add funds first, and ads spend down that balance. When it reaches zero, delivery stops.

    2. Automatic payment: TikTok charges your card when spend reaches your billing threshold or your bill date, whichever comes first.

    3. The switch is one-way. You can move from manual to automatic, but not back.

    4. Most stalled campaigns come from a balance that ran dry (manual) or a threshold charge the card could not cover (automatic).

    The three billing modes in plain terms

    TikTok’s help center describes three billing options (TikTok billing options).

    Manual payment. You add money to the ad account or Business Center before ads run. TikTok calls this a cash balance. Ads deliver against it, and TikTok will not deliver beyond it. If the balance is too low, campaigns can be paused or rejected. Money left over after a campaign carries forward to the next one.

    Automatic payment. You keep a primary payment method on file. TikTok adds up your ad costs and charges that method when the account reaches its billing threshold or its bill date, whichever comes first. Bill dates can be weekly or monthly, and TikTok sets them from the account’s registration date and spending history. A busy account can be charged several times in one cycle, because every time accrued spend reaches the threshold, a new charge fires.

    Monthly invoicing. This is only for eligible businesses. TikTok sets the spending limit and threshold at its discretion, sends an invoice, and payment is due 30 days from the invoice date unless otherwise agreed. Most new advertisers will not see this option.

    ModeWhen money movesWhat stops your adsSuitsCan switch to
    Manual paymentBefore ads run (you add funds)Balance reaches zeroNew advertisers, fixed budgets, prepaid fundingAutomatic or monthly invoicing
    Automatic paymentAfter spend, at threshold or bill dateA failed chargeSteady spend on an established cardMonthly invoicing only
    Monthly invoicingAfter the month, by invoiceAn unpaid invoice past its termsEstablished businesses TikTok approvesNothing else

    The one-way door: why your first choice matters

    TikTok’s automatic payment article is explicit: once automatic payment is set, you cannot go back to manual payment. The allowed moves are manual to automatic, manual to monthly invoicing, and automatic to monthly invoicing. Nothing moves back toward manual.

    That makes manual payment the safer default for a new account. You can test creative, learn your real cost per day, and move to automatic later once you know what a typical charge looks like. If you start on automatic and your card turns out to be a poor fit, the fix is a new payment method, not a different mode.

    Two other settings are worth getting right at the start, because they are hard to change later:

    • Account currency. If your card settles in USD and your ad account bills in another currency, every charge carries a currency conversion. That can add cost, and it makes reconciliation harder. [VERIFY: whether TikTok lets advertisers change ad account currency after creation.]
    • Business details and country. The country and business information on the ad account decide which payment methods you are offered and which advertising policies apply. A different card does not change those rules.

    How automatic payment actually charges your card

    Under automatic payment, each charge is a card-not-present authorization that TikTok’s processor sends to your card issuer. Nobody is at the keyboard when it happens. The issuer checks the card’s status, the available balance, the merchant category, any spending limits, and its own fraud rules. Then it approves or declines.

    New accounts usually start with a low threshold that can rise as payments succeed [VERIFY: TikTok’s threshold starting level and increase rules; they are not stated on the automatic payment page]. The arithmetic is simple. Suppose, as an illustration, your threshold is $200 and the campaign spends $150 a day. You would see a charge roughly every 32 hours, plus one on the bill date for whatever has accrued since the last charge.

    When a charge fails, the decline reason usually maps to one of a few ISO 8583 response codes:

    • 51, insufficient funds. The card balance did not cover the threshold amount. This is the most common cause on prepaid cards.
    • 05, do not honor. A generic issuer refusal, often a risk rule or a merchant-category block.
    • 54, expired card. The card on file has passed its expiry date.

    TikTok says you may need to make a manual payment when your payment method fails. Repeated failures can pause running campaigns or block new ones until the outstanding amount is paid [VERIFY: the number of failed attempts before TikTok pauses campaigns].

    How manual payment keeps a campaign alive

    With manual payment, the balance is your budget fence. The sizing rule is:

    Balance needed = daily budget × days until your next planned top-up + a buffer.

    A campaign spending $80 a day that you top up every Monday needs at least $560 on the balance, plus a margin for days when delivery runs hot. Funds you add by card may take time to appear on the balance, so top up before the balance gets low, not after delivery stops [VERIFY: how long card top-ups take to post to a TikTok balance].

    Manual payment also suits prepaid cards for a structural reason. The card is only used when you choose to add funds, so you are present for the transaction. If the issuer asks for a 3D Secure challenge, you can complete it. An unattended threshold charge cannot answer a challenge.

    Whether TikTok accepts a prepaid card at all depends on the market and the payment methods offered to your account. TikTok’s billing page says the options “may accept bank transfers, credit card, or other payment methods” but does not mention prepaid cards [VERIFY: TikTok’s accepted card types by region, including prepaid].

    Where a crypto-funded prepaid card fits, and where it doesn’t

    Some advertisers hold their working capital in stablecoins and want a card they can fund from a wallet. VCCBuy’s TikTok Ads card page is one worked example. You fund a USD balance with USDT (TRC20, BEP20, ERC20, Polygon or Solana), USDC or several other coins. Deposits are checked before they are credited. You then issue a prepaid Mastercard or Visa. The Mastercard Prepaid has a 2.5% top-up fee and a $10,000 monthly limit. 3D Secure codes are shown in the dashboard for 10 minutes, without a phone number. You can save a billing name and address per card and freeze a card between campaigns.

    Be clear about the limits. Some merchants and some billing settings decline prepaid cards. VCCBuy is not a bank, it does not take BTC deposits (you swap to a stablecoin first), and TikTok makes its own checks regardless of the card. Other legitimate options include a bank-issued virtual card, a business credit card, or bank transfer where TikTok offers it.

    The account rules do not change with the card. TikTok’s country, business-verification and advertising policies apply to every advertiser. If an account is restricted, the route is TikTok’s appeal process, not a new card or a new account.

    Pre-launch billing checklist

    ☐  Billing mode chosen on purpose. Start on manual unless you already know your spend pattern.

    ☐  Ad account currency matches the currency your card settles in.

    ☐  Business name, country and address in Ads Manager are accurate and match the billing details saved on the card.

    ☐  The card is enabled for online, card-not-present and international transactions.

    ☐  You know how to complete a 3D Secure challenge on this card.

    ☐  Manual: the balance covers every day until your next top-up, plus a buffer of at least one extra day.

    ☐  Automatic: the card balance always covers one full threshold charge plus a day of spend.

    ☐  Payment notification emails go to an inbox someone reads daily.

    ☐  A recurring calendar reminder for top-ups or card balance checks.

    When a campaign stalls: a five-step procedure

    1.  Read the exact message in Ads Manager’s payment section. “Insufficient balance” and “payment failed” are different problems.

    2.  Manual payment: add funds and confirm they posted to the balance. Then check whether paused campaigns resumed or need to be switched back on [VERIFY: whether TikTok resumes paused campaigns automatically after a top-up].

    3.  Automatic payment: open the card’s transaction log. A declined authorization with a reason (insufficient funds, expired) tells you the fix. Top up or replace the card, then settle the outstanding amount from the payment section.

    4.  No attempt on the card at all? Then the block is on TikTok’s side, such as payment-method verification or an account review. Contact TikTok support. Changing cards will not help.

    5.  Do not open a second ad account to get around a payment hold. That breaks TikTok’s terms and usually makes the original problem harder to resolve.

    FAQ

    Can I switch from automatic payment back to manual payment? No. According to TikTok’s help center, automatic payment cannot be changed back to manual. You can only move on to monthly invoicing if you become eligible.

    Why was I charged several times in one week? Under automatic payment, TikTok charges each time accrued spend reaches your billing threshold, and again on the bill date. A daily budget above your threshold produces more than one charge per day.

    Does TikTok accept prepaid cards? It depends on your market and the payment methods your account is offered. TikTok’s billing page does not address prepaid cards directly. If a prepaid card is declined at setup, try manual payment first, where you are present for each transaction.

    Conclusion

    TikTok billing is simple once you see where money moves. Manual payment spends a balance you control, and automatic payment charges whatever card is on file at each threshold. Start manual, size the balance to your real daily spend, and move to automatic only when you know your charges. If you fund ads from stablecoins, a VCCBuy prepaid card with a lean, planned balance is one option worth comparing with your bank’s virtual cards.

    About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write about how ad platforms bill cards and how advertisers can keep campaigns running within each platform’s rules.

    Disclosure: the author writes for VCCBuy, which is mentioned in this article.

  • How to Build Integration Flows in SAP Cloud Platform Integration

    How to Build Integration Flows in SAP Cloud Platform Integration

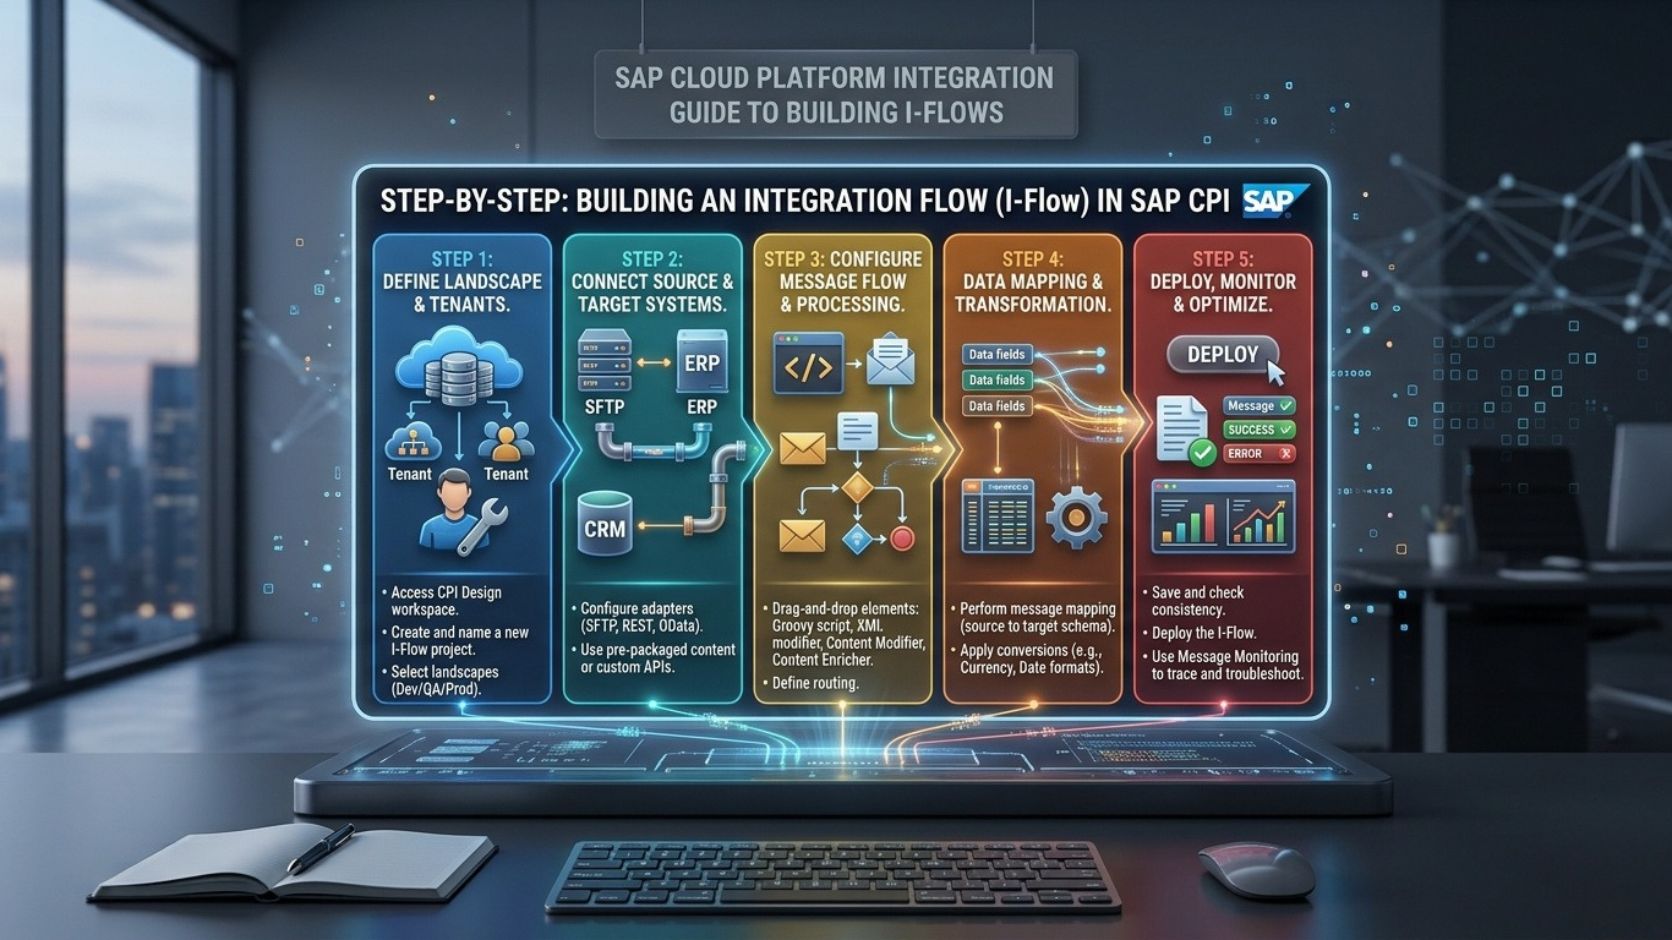
    SAP Cloud Platform Integration provides a cloud-based environment for connecting SAP applications, non-SAP systems, APIs, databases, and external business platforms. Integration flows are the main building blocks used to define how information moves between these systems.

    SAP Cloud Platform Integration is commonly called SAP CPI. The capability is now part of SAP Integration Suite and is generally referred to as Cloud Integration. An integration flow can receive a message, transform its data, apply business logic, route the message, and deliver it to a target system.

    For beginners, understanding how to build an integration flow requires knowledge of sender and receiver systems, adapters, message mapping, content modification, routing, security, deployment, testing, and monitoring. Destinations can also be relevant when applications need centrally configured connection information.

    What Is an Integration Flow?

    An integration flow, commonly called an iFlow, defines how a message travels between systems.

    A basic integration flow contains a sender, processing logic, and receiver.

    Sender System → Integration Flow → Receiver System

    For example, an e-commerce application can send an order to SAP Cloud Platform Integration. The integration flow can receive the order through an HTTP interface, validate the data, transform the message, and send the processed order to SAP S/4HANA.

    An integration flow can contain several processing steps. The exact design depends on the business process and technical requirements.

    How SAP Cloud Platform Integration Works

    SAP Cloud Platform Integration processes messages through a runtime environment.

    The sender system starts the communication. A sender adapter receives the message. The integration flow then processes the message using configured components.

    Processing may include data transformation, message mapping, filtering, routing, validation, or scripting.

    The receiver adapter then sends the processed message to the target system.

    A typical flow can look like:

    Source → Sender Adapter → Mapping → Router → Receiver Adapter → Target

    This structure allows different systems to communicate even when they use different data formats or protocols.

    What You Need Before Building an Integration Flow

    Before creating an integration flow, the source and target systems should be clearly identified.

    You should know the communication protocol supported by each system. This may be HTTP, REST, SOAP, SFTP, OData, IDoc, or another supported technology.

    The source and target data structures should also be available. This is important when message mapping is required.

    Authentication information must also be configured securely.

    For API-based integrations, the endpoint, HTTP method, request structure, response structure, and authentication method should be known before development begins.

    A clear technical design reduces errors during implementation.

    Step 1: Define the Integration Requirement

    The first step is to define what information needs to move between the systems.

    For example, consider a customer synchronization scenario between SAP S/4HANA and a CRM application.

    The requirement may be:

    SAP S/4HANA → Customer Data → CRM Platform

    The design should identify which fields are required.

    For example:

    Customer ID

    Customer Name

    Email Address

    Phone Number

    Country

    The integration should also define whether the process is synchronous, asynchronous, scheduled, or event-driven.

    The expected message volume and frequency should also be considered.

    Step 2: Identify the Sender and Receiver

    The sender is the system that provides the initial message.

    The receiver is the system that receives the processed information.

    For example, SAP S/4HANA can be the sender while Salesforce is the receiver.

    In another scenario, Salesforce can send information to SAP S/4HANA.

    The direction of communication determines the sender and receiver configuration.

    Some integration scenarios can also contain multiple receivers. A router can direct different messages to different target systems.

    Step 3: Create the Integration Flow

    After defining the requirement, the integration flow can be created in the SAP integration environment.

    The developer defines the integration process and adds the required components.

    The initial flow normally contains a sender and receiver connection.

    The graphical development environment allows processing components to be placed between them.

    The flow can then be configured according to the business process.

    Step 4: Configure the Sender Adapter

    The sender adapter determines how the integration flow receives information.

    The appropriate adapter depends on the source system.

    For example, an HTTP adapter can receive requests from an HTTP-based application or REST API.

    A SOAP adapter can receive SOAP messages.

    An SFTP-based scenario can receive files from an SFTP server.

    An IDoc-based integration can use the appropriate SAP connectivity mechanism.

    The adapter configuration normally includes endpoint and authentication-related settings.

    Step 5: Configure the Receiver Adapter

    The receiver adapter determines how the integration flow sends information to the target system.

    For example, an HTTP receiver adapter can call an external REST API.

    A SOAP receiver adapter can communicate with a SOAP service.

    An SFTP receiver can transfer a file to an SFTP server.

    The receiver configuration depends on the protocol, endpoint, authentication method, and target system requirements.

    Step 6: Configure Destinations

    Destinations can be used in SAP cloud environments to provide connection information for applications and services.

    A Destination can contain information such as the target URL, authentication configuration, and other connection properties.

    For example, an application may need to communicate with an external API. Instead of storing the endpoint and authentication configuration directly inside application logic, a configured Destination can provide the required connection information.

    Destinations are particularly relevant when the same application needs different connection settings for development, testing, and production.

    For example:

    Development → Test Endpoint

    Production → Live Endpoint

    Using Destinations can help separate environment-specific connection configuration from application logic.

    The exact Destination configuration depends on the target service and authentication method.

    Step 7: Add Message Mapping

    Message mapping is required when the source and target systems use different data structures.

    For example, the source system may send:

    customer_id

    customer_name

    email

    The target system may require:

    CustomerNumber

    FullName

    EmailAddress

    A mapping connects the source fields to the required target fields.

    Mapping can also transform values, combine fields, apply conditions, and convert data types.

    For example, FirstName and LastName can be combined into a FullName field.

    Message mapping should match the target system’s interface requirements.

    Step 8: Add Content Modifiers

    Content modifiers can change message headers, properties, and message bodies.

    They can be used when additional information needs to be added to the message during processing.

    For example, a property can store an order number or another value that is needed later in the integration flow.

    Content modifiers can also prepare a message before it reaches another processing step.

    The configuration depends on the information required by the integration scenario.

    Step 9: Add Routing Logic

    A router allows the integration flow to make decisions based on message content or other conditions.

    For example, an order integration can use the country field to determine the target system.

    An order from Germany can follow one processing path, while an order from the United States can follow another.

    The structure can be represented as:

    Incoming Message → Router → Condition A / Condition B → Different Processing Paths

    Routing is useful when a single integration flow needs to support multiple business scenarios.

    Step 10: Transform the Message

    The source and target systems may use different data formats.

    For example, the source may provide XML while the target API requires JSON.

    The integration flow can transform the message into the format expected by the receiver.

    Transformation can include changing field names, converting data types, restructuring content, and modifying values.

    The transformation method should match the target system’s interface specification.

    Step 11: Add Validation

    Validation helps ensure that required information is available before the message reaches the target system.

    For example, an order may require:

    Order ID

    Customer ID

    Product ID

    Quantity

    If a required field is missing, the message can be routed to an error-handling process instead of being sent to the target system.

    Validation can reduce unnecessary requests to target systems and make integration errors easier to identify.

    Step 12: Configure Authentication and Security

    Security configuration depends on the source and target systems.

    Common authentication methods include OAuth, basic authentication, client certificates, and other supported methods.

    HTTPS can protect data during transmission.

    Authentication information should be stored using secure configuration mechanisms.

    Sensitive credentials should not be unnecessarily exposed in scripts, message bodies, or integration logs.

    Security requirements should be defined before the integration flow is deployed.

    Step 13: Add Error Handling

    Integration flows should account for technical and business errors.

    A technical error can occur when a target system is unavailable. Authentication can also fail because credentials are incorrect or expired.

    A business error can occur when required data is missing or invalid.

    SAP Cloud Platform Integration provides exception-handling capabilities that can be incorporated into integration flows.

    An exception subprocess can capture an error and execute a separate processing path.

    For example:

    Processing Error → Exception Subprocess → Error Handling

    The error-handling process can log the problem or send information to another system, depending on the integration requirements.

    Step 14: Test the Integration Flow

    Testing should be performed before production deployment.

    The test should use realistic message structures and values.

    For example, an order integration should test valid orders and invalid orders.

    The test should verify whether the sender can communicate with the integration endpoint, whether mapping works correctly, and whether the receiver accepts the final message.

    Authentication and error conditions should also be tested.

    Testing can identify configuration problems before the integration is used for live business transactions.

    Step 15: Deploy the Integration Flow

    After testing, the integration flow can be deployed to the runtime environment.

    Deployment makes the integration artifact available for message processing.

    The developer or administrator should confirm that the required connection configuration, authentication, endpoints, and other dependencies are available.

    If Destinations are used, the appropriate Destination configuration should also be available in the relevant environment.

    Development, testing, and production environments can have different endpoint and authentication configurations.

    Step 16: Monitor Message Processing

    After deployment, message processing should be monitored.

    Monitoring can show whether messages are successful or failed.

    If a message fails, the processing information can help identify the problem.

    Common causes include:

    • Invalid credentials
    • Incorrect endpoint
    • Mapping errors
    • Missing fields
    • Target-system errors
    • Network problems

    Monitoring information can be used to troubleshoot the integration and improve reliability.

    Example: Building an S/4HANA to CRM Integration

    Consider an integration where SAP S/4HANA sends customer information to a CRM platform.

    The architecture can be:

    SAP S/4HANA → Integration Flow → CRM Platform

    The sender adapter receives the customer information.

    The integration flow validates required fields such as customer ID and email address.

    Message mapping then converts the S/4HANA structure into the CRM structure.

    A content modifier can add required metadata.

    The receiver adapter sends the transformed message to the CRM API.

    If the CRM API rejects the request, the exception-handling process can capture the failure.

    The message can then be reviewed through monitoring.

    Example: API-Based Integration Flow

    An API integration can use the following structure:

    External Application → HTTP Endpoint → Cloud Integration → Mapping → Target API

    The external application sends a request.

    The sender endpoint receives the request.

    The integration flow validates and transforms the data.

    The receiver adapter calls the target API.

    The response can then be processed and returned to the calling application when the integration pattern requires a response.

    This approach is common when cloud applications need to exchange data through REST APIs.

    Common Mistakes When Building Integration Flows

    Integration flow problems can occur when technical requirements are not defined clearly.

    Using the wrong adapter can prevent communication. Incorrect field mappings can produce invalid data. Missing authentication configuration can cause authorization failures.

    Another common problem is insufficient error handling. Without proper exception processing, identifying the cause of failed messages can take longer.

    Incorrect endpoint configuration can also cause connection failures.

    Connection information should be checked carefully, particularly when different development, testing, and production environments are used.

    Destinations should also be configured consistently when they are part of the integration architecture.

    Best Practices for Building Integration Flows

    Integration flows should have clear names and organized processing steps.

    Only required processing components should be included. Unnecessary transformations can increase complexity.

    Authentication information should be handled securely.

    Error handling should be designed before production deployment.

    Message mappings should match the current source and target interface specifications.

    Testing should include both successful and failed scenarios.

    Monitoring should be used after deployment to identify message-processing problems.

    Environment-specific connection settings should be separated from core integration logic where the architecture supports this approach.

    Frequently Asked Questions

    What is an integration flow in SAP Cloud Platform Integration?

    An integration flow is a graphical representation of the processing logic used to move messages from a sender system to a receiver system. It can contain adapters, mappings, routers, transformations, and error-handling components.

    How do I start building an integration flow?

    Start by identifying the source and target systems, communication protocols, message structures, authentication requirements, and business rules. Then create the integration flow and configure the required sender, processing, and receiver components.

    What are Destinations used for?

    Destinations provide connection information that applications and services can use to communicate with target systems. They can contain endpoint and authentication configuration.

    Can Destinations be used for different environments?

    Yes. Destinations can provide environment-specific connection information. Development, testing, and production environments can use different target endpoints and authentication configurations.

    Which adapters can be used in an integration flow?

    The available adapter depends on the integration scenario. Common technologies include HTTP, SOAP, SFTP, OData, IDoc, and ProcessDirect.

    What is message mapping?

    Message mapping converts source data into the structure required by the target system. It can connect fields, change values, combine data, and convert data types.

    How do I test an integration flow?

    Testing should verify connectivity, authentication, message structure, mapping, routing, target-system communication, and error handling. Both successful and failed scenarios should be tested.

    How are integration flow errors handled?

    Errors can be processed through exception-handling mechanisms. Failed messages can be investigated using message-processing and monitoring information.

    Is SAP Cloud Platform Integration still used?

    The technology has evolved into the Cloud Integration capability within SAP Integration Suite. SAP CPI remains a widely used term for the technology.

    Conclusion

    Building integration flows in SAP Cloud Platform Integration involves several connected stages. The process starts with identifying the source and target systems and selecting the appropriate communication technologies.

    The integration flow then connects these systems through adapters and processing components. Message mapping and transformation ensure that the target system receives the required data structure. Routing and validation can apply business rules, while security protects communication and access.

    Destinations can provide structured connection information for applications and services. They can also help separate environment-specific connection settings from application logic.

    After development, the integration flow should be tested, deployed, and monitored. Error handling should also be included so that technical and business failures can be identified and managed.

    With these components working together, SAP Cloud Platform Integration can support integration between SAP S/4HANA, SAP SuccessFactors, APIs, cloud applications, and third-party systems within a structured enterprise integration architecture.

  • How Open Banking and Card Issuing APIs Are Converging

    How Open Banking and Card Issuing APIs Are Converging

    Open banking APIs and card issuing APIs once served separate roles. That boundary is fading. Shared access to account data, payment initiation, and card controls is creating a more unified financial stack. This shift helps firms verify funds faster, manage risk with better context, and build smoother payment flows. As infrastructure and regulation evolve together, the practical impact of this convergence becomes harder to ignore.

    How Open Banking and Card APIs Differ

    At a basic level, open banking APIs and card issuing APIs serve different functions within financial infrastructure. Open banking APIs enable secure access to account data and payment initiation across institutions, supporting transaction transparency, data privacy, and stronger consumer trust. Their value often depends on API security standards, consent management, and clearer financial literacy for users reviewing shared data.

    Card issuing APIs, by contrast, let businesses create, manage, and control payment cards for spending. They focus on authorization rules, card lifecycle management, and embedded payment flows that shape user experience at the point of purchase.

    While both can influence market competition and innovation acceleration, card issuing APIs are primarily operational tools for disbursements, expenses, and branded payments, rather than mechanisms for broad account connectivity or standardized financial data access.

    Why Banking and Card Issuing Are Converging

    The convergence of banking and card issuing is being driven in part by shared infrastructure, as providers increasingly rely on common API frameworks, compliance controls, and payment rails.

    It is also being accelerated by real-time data synergies that improve authorization, fraud monitoring, and account-based decisioning.

    Together, these shifts are supporting a more unified embedded finance model in which banking and card functionality are delivered through integrated platforms.

    Shared Infrastructure Drivers

    As digital finance platforms have matured, open banking and card issuing have increasingly relied on the same underlying infrastructure: APIs, cloud-native processing, identity verification, fraud controls, and real-time ledgering.

    This shared infrastructure reduces duplication across product lines and enables providers to build once, then extend capabilities across payments, account access, onboarding, and compliance workflows.

    API standardization has further accelerated convergence by making integration patterns more predictable for fintechs, banks, processors, and enterprise platforms.

    Common authentication methods, modular service layers, and reusable orchestration tools support faster deployment while lowering operational complexity.

    The same vendors often now supply tokenization, KYC, transaction monitoring, dispute management, and ledger services to both banking and issuing programs.

    As a result, institutional boundaries matter less than technical architecture, platform design, and the economics of scalable financial software.

    Real-Time Data Synergies

    Shared infrastructure has made convergence technically feasible, but real-time data flows are making it commercially and operationally compelling. As banking and card issuing APIs interact more closely, data interoperability enables faster decisions across payments, account activity, and funding events.

    Providers can combine transaction analytics with customer insights to refine authorization logic, detect anomalies, and strengthen risk management without adding operational friction.

    These synergies also improve user experience by supporting timely notifications, balance-aware spending controls, and more accurate cash-flow visibility. Real-time signals can expand financial inclusion by helping providers assess behavior beyond traditional credit metrics and respond to changing circumstances quickly.

    At the market level, continuous data exchange creates innovation opportunities, allowing firms to test responsive products and deepen ecosystem collaboration among banks, issuers, fintechs, and processing partners globally.

    Unified Embedded Finance

    Convergence in embedded finance is being driven by demand for unified products that combine account functionality, payment issuance, and programmable controls within a single user experience.

    This shift reflects a broader market preference for fewer integrations, faster deployment, and more consistent financial workflows across digital platforms.

    What’s Driving This Convergence?

    Several market forces are accelerating the convergence of open banking and card issuing APIs. Institutions are pursuing stronger customer experience through faster onboarding, smoother payments, and more responsive financial services.

    Technology evolution and digital transformation have lowered integration barriers, while market competition is pushing providers to differentiate with flexible, data-driven offerings. Regulatory changes in many regions are also encouraging standardized access, transparency, and portability across financial ecosystems.

    At the same time, consumer demand for convenience, personalization, and real-time control continues to rise. Providers are responding through innovation trends that support broader financial inclusivity and more tailored products.

    Stronger security measures remain essential as data sharing expands, prompting investment in authentication, monitoring, and compliance. Industry partnerships further accelerate progress by combining infrastructure, distribution, and specialized capabilities across banks, fintechs, and platforms.

    Bridging Local Users and Global Commerce

    In many markets, the gap between local payment habits and global online commerce remains wide: international checkout pages expect card credentials that local banking products don’t always provide. API-issued virtual cards bridge that gap at software speed. Nigeria is one of the clearest examples of this dynamic, and the growth of the virtual card API in Nigeria ecosystem shows how quickly access expands when issuance becomes an integration rather than a banking relationship.

    How Open Banking and Card APIs Work Together

    Open Banking and card issuing APIs operate together by linking bank account data with card-based payment capabilities.

    This enables real-time account verification, which supports faster onboarding, stronger fraud controls, and more accurate transaction approval.

    It also supports unified payment flows by connecting funding, authorization, and settlement processes across account-to-account and card transactions.

    Real-Time Account Verification

    Linking bank-account data with card issuing workflows enables real-time account verification at the moment of onboarding or funding. By combining open banking access with issuer controls, platforms can confirm account ownership, status, and recent activity before enabling a card or approving an initial load. This reduces manual review, accelerates activation, and improves decision accuracy.

    Open banking APIs supply authenticated account details, while card issuing systems apply those signals to compliance, fraud screening, and operational rules. The result is real-time verification supported by current financial data rather than static user inputs alone.

    Account synchronization further helps keep records aligned when account credentials, balances, or permissions change. In practice, this convergence supports faster onboarding, fewer failed funding attempts, and stronger confidence that linked accounts are valid, active, and authorized.

    Unified Payment Flows

    Unify payment orchestration by combining open banking connectivity with card issuing APIs into a single flow for funding, disbursement, and transaction control.

    This model creates unified interfaces that support streamlined transactions across bank transfers, virtual cards, and physical cards. It improves customer experience by reducing handoffs between systems while enabling enhanced security through tokenization, authentication, and real-time account validation.

    Converged payment stacks also advance payment innovation by linking account data, card controls, and settlement logic within one operational framework.

    The result is stronger cost efficiency, faster technology integration, and better data analytics for risk monitoring and product design.

    How Real-Time Data Improves Card Issuing

    Real-time data strengthens card issuing by giving providers immediate visibility into account balances, transaction activity, and customer behavior. This access supports data driven insights that refine authorization decisions, improve enhanced security controls, and reduce unnecessary declines.

    Issuers can adjust dynamic limits in response to changing risk profiles or spending patterns, creating more accurate controls without delaying use.

    Real time personalization also improves the user experience by aligning card settings, alerts, and rewards with current activity. With predictive analytics, providers can anticipate anomalies, identify high value moments, and support instant approvals where risk appears acceptable.

    The result is more frictionless transactions, faster responses to customer needs, and a card program that operates with greater precision, adaptability, and reliability in competitive digital payment environments today.

    How Card Issuing Extends Open Banking

    Card issuing extends open banking by turning shared financial data into a usable payment instrument. Through API integration, institutions can connect account data, payment initiation, and issuance workflows within a unified framework.

    This convergence improves the cardholder experience by aligning spending tools with verified financial context and stronger user authentication.

    It also broadens the value of open banking beyond access and aggregation. Issuers can derive transaction insights that support personalized offerings, stronger customer engagement, and more adaptive controls.

    These capabilities enable innovative solutions while reinforcing security measures and regulatory compliance across onboarding, funding, and authorization processes.

    In parallel, card issuing can support financial inclusion by translating account visibility into practical, everyday payment access.

    Together, these layers make open banking more actionable, measurable, and commercially relevant for providers and end users alike.

    Top Use Cases for Open Banking and Cards

    These combined capabilities are most visible in the practical use cases they support across payments, lending, expense management, and digital commerce.

    • Instant account-to-card funding supports open banking innovation.
    • Real-time underwriting improves card issuing efficiency.
    • Smarter controls strengthen transaction security measures.
    • Personalized rewards drive user engagement strategies.
    • Seamless checkout advances digital wallet integration.

    Together, these applications enable customer experience enhancement through faster onboarding, verified identity, and clearer spending insights.

    They also widen financial inclusion impact by helping underserved users access tailored credit, prepaid products, and low-friction payment tools.

    For merchants and platforms, the model creates fintech collaboration opportunities around payouts, subscriptions, and embedded budgeting features.

    The result is a more responsive financial ecosystem that links data access with programmable card distribution and measurable commercial value across consumer and business journeys today.

    How Embedded Finance Teams Build With Both

    Embedded finance teams typically combine open banking connectivity with card issuing APIs by designing a unified product stack that links account data, payment initiation, identity checks, and programmable spending tools. This approach supports embedded finance models that prioritize API integration, consistent user experience, and stronger transaction efficiency across onboarding, funding, and payout flows.

    Teams usually align product, compliance, and operations functions around shared innovation strategies, using open banking for verification and account access while using cards for controlled disbursement and spend management.

    The result is cost reduction through fewer intermediaries, reinforced security measures through layered controls, and broader scalability options as volumes grow. By responding to market trends with modular architecture, firms can adapt faster, launch differentiated services, and build a measurable competitive advantage in increasingly connected financial ecosystems.

    What Developers Need From a Unified API

    Because integration complexity rises quickly across payment, account, and compliance workflows, developers need a unified API that presents open banking and card issuing functions through consistent authentication, standardized schemas, and predictable event handling.

    Strong developer experience depends on API standardization that reduces integration challenges and supports reusable components across products. Teams also expect scalability solutions, resilient security protocols, efficient user authentication, and documentation clarity that shortens onboarding and debugging cycles.

    • Consistent endpoints accelerate implementation
    • Clear webhooks improve system reliability
    • Testing frameworks reduce deployment risk
    • Version control limits breaking changes
    • Support resources speed issue resolution

    A capable platform aligns data models, sandbox behavior, and production performance. It enables faster iteration while preserving observability, reducing maintenance overhead, and helping engineering teams deliver connected financial features with greater confidence across markets.

    Compliance Risks in Converged Payments

    Converged payments introduce compliance complexity by placing open banking and card issuing activities under overlapping regulatory frameworks.

    This structure increases exposure to data sharing liabilities, particularly where consent management, data handling, and third-party access intersect.

    It can also create fraud monitoring gaps when controls are fragmented across systems, providers, or payment rails.

    Regulatory Overlap Challenges

    Three overlapping regulatory regimes often shape the risk profile of open banking and card issuing integrations: payments law, data protection rules, and card network requirements. Their convergence complicates regulatory compliance because firms must align legal frameworks, consumer protection duties, and industry standards across distinct operational models.

    Supervisory expectations may diverge by jurisdiction, while interoperability issues between banking APIs and card rails increase control complexity. Effective risk management therefore requires mapped obligations, coordinated governance, and auditable processes that support data privacy without slowing product delivery.

    Overlap can also create innovation barriers when approvals, technical certifications, and monitoring obligations duplicate effort.

    • Conflicting rules across products and markets
    • Divergent supervisory interpretations
    • Higher control and audit burdens
    • API and network interoperability issues
    • Slower launches from layered compliance demands

    Data Sharing Liabilities

    As overlapping rules increase governance complexity, liability exposure in data sharing becomes a central compliance concern for firms combining open banking connections with card issuing functions.

    Questions around data ownership, permitted use, retention, and onward transfer often remain contested across providers, processors, and banking partners. Clear consumer consent records are therefore essential to support lawful processing and dispute resolution.

    Where responsibilities are fragmented, liability shifts can occur after service failures, inaccurate disclosures, or unauthorized access to shared information.

    Effective risk management depends on harmonized compliance frameworks that define contractual duties, audit rights, breach notification timelines, and accountability standards.

    Strong data privacy controls and proportionate security measures help reduce exposure, but legal clarity remains critical when multiple entities collect, transmit, and monetize customer financial data across integrated payment ecosystems.

    Fraud Monitoring Gaps

    A persistent challenge in converged payments is the emergence of fraud monitoring gaps between open banking data flows and card issuing controls. Different rails often apply separate fraud detection rules, inconsistent risk scores, and uneven escalation paths. As a result, suspicious behavior may appear low risk in one system while triggering alerts in another, weakening transaction monitoring and delaying intervention.

    • Fragmented visibility across payment channels
    • Inconsistent customer authentication signals
    • Delayed alert sharing between providers
    • Conflicting case management procedures
    • Greater exposure to compliance breaches

    These gaps create operational blind spots for regulated firms. Institutions must align data standards, alert taxonomies, and response protocols across providers.

    Without coordinated oversight, reconciled records may satisfy reporting requirements while underlying fraud patterns remain undetected, increasing losses, investigation burdens, and scrutiny from regulators and banking partners.

    How Converged Payments Drive Fintech Growth

    Momentum in fintech often comes from converged payments, where open banking, card issuing, and embedded payment services operate through coordinated APIs rather than isolated systems.

    These converged channels strengthen payment ecosystems by reducing friction across account-to-account transfers, card rails, and digital wallets.

    As integration deepens, fintech innovation accelerates through faster launches, broader product design, and better user experience.

    Improved transaction speed supports retention, while stronger risk management across unified data flows helps sustain consumer trust.

    Convergence also sharpens market competition, allowing newer firms to challenge incumbents with lower costs and more adaptive services.

    In emerging and underserved segments, interoperable payment models can extend financial inclusion by connecting users, merchants, and platforms through flexible payment options.

    The result is scalable growth built on connectivity, efficiency, and more responsive financial infrastructure overall.

    Frequently Asked Questions

    How Long Does Integrating Both APIS Typically Take?

    It typically takes six weeks to six months to integrate both APIs, depending on complexity, compliance, and vendor readiness. The integration timeline varies with internal resource allocation, technical debt, testing requirements, and stakeholder coordination.

    Which Regions Have the Strongest Support for Converged Payment Infrastructure?

    Europe shows the strongest support, driven by European innovations; parts of Asia follow through Asian regulations, while North American trends remain robust but fragmented. Market challenges persist globally, including interoperability, licensing complexity, bank participation, and varied compliance standards.

    What Internal Teams Should Own Unified Banking and Card API Projects?

    Unified banking and card API projects should be owned by development teams with strong technical expertise, supported by clear project ownership, stakeholder involvement, collaboration strategies, and disciplined resource allocation across product, compliance, operations, and security functions.

    How Do Pricing Models Differ Between Open Banking and Card Issuing APIS?

    Open banking APIs typically use usage-based pricing strategies, subscription tiers, or freemium access, while card issuing APIs more often combine setup fees, per-card charges, interchange sharing, and compliance costs within broader revenue models structures.

    What Vendor Selection Criteria Matter Most for Long-Term Scalability?

    The theory that features alone ensure growth rarely holds; the decisive criteria are vendor reliability, scalability potential, integration flexibility, compliance standards, support services, and technology compatibility, which collectively determine whether long-term expansion remains operationally sustainable.

    Final words

    The convergence of open banking and card issuing APIs marks a significant shift in financial infrastructure. By combining real-time account data with flexible card controls, institutions can improve security, efficiency, and customer experience. This unified approach supports faster innovation, stronger compliance, and broader access to financial tools. As the saying goes, “necessity is the mother of invention.” In converged payments, that necessity is driving a more connected, responsive, and inclusive financial ecosystem for all stakeholders.
  • Virtual Cards for Paying International Course Fees in Ukraine

    Virtual Cards for Paying International Course Fees in Ukraine

    You can use single‑use virtual cards to pay Ukrainian course fees while isolating your primary account and enforcing currency, amount and merchant controls. Confirm invoice currency, beneficiary bank rails and who bears FX before you issue a card for the invoice amount. Capture transaction IDs, timestamps, exchange rates and receipts for audit and KYC screening. Have fallbacks like local transfers or alternative networks for declines. Continue for detailed steps on setup, provider selection and reconciliation.

    Key Takeaways

    • Use single-use virtual cards capped at the invoice amount to protect primary accounts and ensure traceable refunds.
    • Confirm the institution’s accepted currency and who bears exchange-rate costs before issuing the card.
    • Choose providers supporting Ukrainian receiving rails, KYC, and transparent FX/fee schedules for cross-border settlements.
    • Capture transaction IDs, timestamps, exchange rates, and receipts to reconcile against the institution’s ledger and audits.
    • Maintain fallback options (local bank transfer, alternative card network, stablecoins) with documented compliance and reconciliation workflows.

    Quick: Pay a Ukrainian Course Fee in 5 Steps

    1. You’ll first confirm the course invoice details, matching payer name, amount, currency, and any bank identifiers to reduce reconciliation errors.

    Next, you’ll select a virtual card provider that aligns with your international fee strategies and supports the receiving institution’s payment rails.

    Third, you’ll generate a single-use card with limits set to the invoice amount and an expiration that covers settlement windows; this minimizes fraud and ensures compliance.

    Fourth, you’ll execute the payment, capturing transaction IDs, timestamps, and exchange rates to document compliance with digital payment trends and audit trails.

    Finally, you’ll verify settlement and reconcile the institution’s receipt against your ledger, archiving receipts and communication for regulatory and internal review.

    Trimming a Bloated Subscription Stack

    At one stage our subscriptions outnumbered the people in our office. A friend who’d been there clawed control back by moving each to a virtual card for online subscriptions he could watch separately. He recommended Card29, and the fog finally cleared. Every service sits on its own prepaid card with a set cap, so price creep and zombie renewals have nowhere to hide. For anyone whose credit card funds a dozen forgotten apps, that VCC discipline brings the list back to earth.

    How Virtual Cards Work for International Tuition

    When you use virtual cards for international tuition, they act as single-use or limited-use payment instruments that isolate the payer’s primary account details while enforcing issuer-defined controls—currency, amount, merchant category, and expiration—to reduce fraud and simplify cross-border compliance.

    You’ll link cards to digital wallets and set limits that address currency fluctuations and speed reconciliation. Transaction security relies on user authentication, tokenization, and issuer rules; this preserves payment speed while meeting international regulations.

    You’ll see improved user experience because errors are contained and refunds traceable. Consider these operational controls:

    • Limit per-transaction amount and merchant category to enhance fraud prevention.
    • Tokenize card data within digital wallets for secure processing.
    • Set expiration tied to course billing cycles to limit exposure.
    • Monitor for compliance with international regulations and FX variances.

    Providers That Accept Payments to Ukraine

    Moving from how virtual cards control risk and currency exposure, you’ll next need to identify payment providers that actually process fees to Ukraine and meet both operational and compliance requirements.

    You should evaluate banks, global payment processors, and specialized international payment solutions that support Ukranian receiving rails, AML screening, and sanctions filtering.

    Prioritize providers with clear KYC processes, transaction limits aligned with tuition schedules, and audit trails that document virtual card benefits like single-use credentials and spend controls.

    Check provider licensing for cross-border transfers into Ukraine, settlement currency options, and correspondent banking relationships to avoid delays.

    Finally, demand SLA terms for dispute resolution and chargebacks, and verify that reporting formats meet your institution’s compliance and reconciliation needs.

    Ukraine Tuition: Payment and Currency Rules

    Although Ukraine allows tuition to be paid in local hryvnia and certain foreign currencies, you’ll need to confirm acceptable payment currency with the receiving institution and your payment provider to avoid conversion delays or rejected transfers.

    You should verify invoicing currency, exchange-rate responsibility, and any bank intermediary requirements before initiating payment.

    Watch for compliance requirements tied to residency, tax reporting, and sanctioned-entity screening that can block transfers.

    • Confirm currency listed on invoice and permitted payment channels
    • Check for tuition discounts applied only to specific currencies or payment methods
    • Track payment deadlines, cut-off times, and processing lead times for international transfers
    • Retain receipts showing currency, fees, and exchange rate for audit and refund cases

    Plan payments to meet deadlines and avoid noncompliance.

    Set Up a Virtual Card for Tuition Payments

    Having confirmed acceptable invoice currency and payment channels, set up a virtual card to control how and when tuition payments are executed and to document currency conversions and fees for compliance.

    You’ll choose a provider that supports your invoice currency, multi-currency wallets, and exportable transaction reports. Configure single-use or merchant-limited card numbers, spending caps, and expiry dates to limit exposure and support international payment security requirements.

    Link the virtual card to your accounting system and enable automatic reconciliation tags to capture exchange rates and issuer fees for audit trails. Retain PDFs of virtual-card authorizations and statements.

    Test a low-value transaction to verify acceptance and conversion treatment before funding large transfers. This preserves virtual card benefits while meeting AML and reporting obligations.

    Step-by-Step: Pay a Ukrainian Course Fee With a Virtual Card

    Before you initiate payment, confirm the invoice currency, beneficiary details, and any Ukrainian-specific compliance requirements so you can configure the virtual card precisely for the transaction.

    Proceed systematically: check payee name, institution bank details, and required remittance references. Use platforms reflecting international payment trends and compare digital wallet options if institution accepts them.

    Authorize a single-use virtual card or set appropriate spend controls, then fund it and record the card number, expiry, and CVV securely.

    Submit payment through the university’s portal or bank transfer flow, attaching proof as required for compliance.

    • Verify beneficiary legal name and IBAN/sort code
    • Match invoice reference and program codes
    • Choose single-use vs. multi-use virtual card
    • Retain transaction receipts for audit

    Confirm settlement and follow up until reconciliation completes.

    Minimize Fees: Currency Conversion, Limits and Charges

    When you set up a virtual card for an international tuition payment, optimize currency conversion, limits, and fee settings to avoid unexpected costs: pick the invoice currency that eliminates double conversion, lock the card to the payee’s currency when possible, and choose a funding source or FX option with the best mid-market rate or a transparent markup.

    You should review fixed and percentage-based transaction fees, nightly FX revaluation policies, and any issuer surcharges. Set card limits to cover the exact billed amount plus contingency to prevent declines and avoid incremental fees from multiple attempts.

    Document fee schedules and keep receipts for compliance and reconciliation. Monitor real-time currency exchange indicators and compare provider quotes before authorizing large payments.

    Security Checks, Rejections, and How to Fix Them

    If your virtual card payment is flagged or rejected, treat it as a compliance event and run a structured troubleshooting checklist: You’ll diagnose issues methodically, focusing on security measures, payment verification, fraud prevention, and transaction monitoring.

    Start by gathering system logs, timestamps, and merchant response codes.

    • Confirm card metadata, limits, and currency match invoice details.
    • Verify KYC/beneficiary data and resend payment verification to the provider.
    • Check transaction monitoring alerts for patterns or velocity triggers.
    • Escalate to compliance if evidence shows potential fraud or sanctioned parties.

    You’ll document each step, retain evidence for audits, and apply corrective actions: adjust limits, update payee metadata, or reauthorize with enhanced verification.

    This minimizes repeats and preserves audit trails for regulators.

    Coordinator Workflows: Batch Payments With Virtual Cards

    After you’ve handled flagged or rejected transactions and documented corrective steps, you’ll want a repeatable coordinator workflow for executing batch virtual-card payments that preserves those audit trails and minimizes compliance risk.

    You’ll centralize requests into a secure spreadsheet or payments platform, include standardized justification codes, and require two-step approvals to protect controls.

    Automate card issuance in predictable batches, assign expiration windows, and reconcile authorizations immediately to prevent stale holds.

    Use dedicated fields for coordinator efficiency metrics and embed payment tracking links so auditors can trace each card to invoice, approver, and student record.

    Maintain immutable logs of API calls and reconciliation reports, and schedule routine sampling reviews.

    That discipline reduces errors, demonstrates compliance, and supports rapid internal or external audits.

    When Virtual Cards Fail : Fallback Payment Options

    If a virtual card is declined or blocked, you’ll need a preapproved set of fallback methods — local bank transfers, alternative card networks, and crypto or stablecoins — each mapped to compliance and reconciliation workflows.

    You’ll assess counterparty onboarding requirements, currency conversion controls, and settlement timelines to choose the least disruptive option.

    You’ll also document audit trails and approval thresholds so every fallback payment meets AML and reporting obligations.

    Local Bank Transfers

    When virtual cards decline or aren’t accepted, you’ll typically turn to local bank transfers as the most reliable fallback. These transfers reduce cross-border card friction by settling fees in the payee’s local currency and often comply with domestic AML/KYC rules.

    You’ll evaluate routing options, verify beneficiary details, and confirm SWIFT/BIC or local clearing codes to limit reconciliation delays. Local transfers also mitigate currency conversion unpredictability seen in cross border transactions and align with Ukrainian banking regulations.

    • Verify beneficiary name and account number against official ID to satisfy AML/KYC.
    • Use net settlement or correspondent bank routes to minimize intermediary fees.
    • Confirm daily transfer limits and reporting triggers under banking regulations.
    • Retain transaction receipts and SWIFT confirmations for audit and dispute resolution.

    Alternative Card Networks

    Because card declines can stem from network routing, merchant acceptance rules, or issuer controls, you should have alternative card networks mapped as a primary fallback to virtual cards.

    You’ll identify Visa, Mastercard, MIR, and regional schemes and document routing preferences per merchant to reduce decline loops.

    Assess BIN ranges, cross-border blocking policies, and velocity limits; record issuer contact points for rapid overrides.

    Integrate alternative payment methods like digital wallets that tokenize card details over different networks to preserve transaction continuity while maintaining PCI and PSD2 compliance.

    Define escalation workflows: try primary virtual card, switch network or wallet token, then execute authorized manual capture or bank-assisted transfer if needed.

    Maintain audit trails, consent logs, and periodic testing to validate fallbacks.

    Crypto And Stablecoins

    Although virtual cards and alternative card networks handle most cross-border course fee failures, you should prepare crypto and stablecoin options as a controlled fallback that preserves compliance, auditability, and user consent.

    You’ll evaluate crypto benefits against regulatory risk, implementing KYC/AML checks, transaction monitoring, and clear consent screens. Stablecoin stability reduces FX volatility and simplifies reconciliation, but you must choose vetted issuers and maintain on‑chain/off‑chain records.

    • Define acceptable coins and issuers, emphasizing stablecoin stability and issuer audits.
    • Require enhanced KYC/AML before offering crypto payments.
    • Log immutable transaction proofs plus off‑chain reconciliations for audits.
    • Set thresholds and approval workflows to limit exposure and ensure manual review.

    This approach keeps payments usable, traceable, and compliant.

    Final words

    You’ve now got a pragmatic roadmap to pay Ukrainian course fees with virtual cards. Think of it like a customs checkpoint: one coordinator moved from repeated rejections to seamless batch settlements after adding MCC codes and 3D Secure, cutting declines by 80%. Keep compliance tight—match beneficiary details, respect currency rules, watch limits and FX spreads—and you’ll minimize failures. When virtual cards can’t clear, have vetted wire-transfer or local-processor backups ready.

  • Why Travelers in Switzerland Carry a Virtual Card

    Why Travelers in Switzerland Carry a Virtual Card

    You carry a virtual card in Switzerland to make fast, secure contactless payments, limit fraud from hotel and transit pre‑authorizations, and control spending with per‑vendor limits and real‑time alerts. Issuance is instant via an app, supports NFC wallets, and lets you use disposable numbers for bookings to avoid card theft. Expect small foreign‑transaction fees and daily limits, so keep a backup. Learn practical setup, acceptance points, and fee comparisons to use them confidently.

    Key Takeaways

    • Virtual cards reduce fraud risk by using single‑use or tokenized numbers for hotel bookings, rentals, and online reservations.
    • Instant issuance lets travelers get a usable card in minutes without needing a physical bank branch.
    • Linking virtual PANs to mobile wallets enables quick NFC contactless payments on trains, shops, and restaurants.
    • Separate virtual cards simplify budget tracking and expense control for transport, lodging, and meals.
    • Issuers offer instant freezing, spend limits, and real‑time alerts to stop unauthorized transactions quickly.

    What a Virtual Card Is and How It Works in Switzerland

    Although you won’t hold anything physical in your wallet, a virtual card works just like a regular debit or credit card for online and contactless payments: it’s a digitally issued card number, CVV, and expiry tied to your bank or card provider that you can use immediately in apps, browsers, or mobile wallets.

    You’ll get tokenization, single-use or limited-life numbers, and spend controls that reduce fraud exposure — key elements of digital security. In Switzerland, issuers comply with PSD2 and local AML rules, so transaction authentication and dispute procedures match standards you expect.

    You’ll enjoy payment convenience: instant issuance, easy card rotation, and per-merchant limits. Track transactions in your banking app, freeze cards instantly, and minimize liability without carrying extra plastic.

    Quick Start: Get a Virtual Card While Traveling

    When you land, get a virtual card in minutes by using your bank’s app or a reputable fintech—most Swiss banks and international providers issue cards instantly with tokenization and merchant-specific limits.

    Open the app, verify identity (usually selfie+ID or biometric), choose a single-use or multi-use virtual PAN, set currency and daily cap, and activate. Expect issuance in under five minutes; confirmation and token provisioning occur immediately for contactless wallets (next section covers wallet setup).

    Use the card for transit, hotels, and online bookings to realize virtual card benefits: reduced fraud surface, enforceable spend controls, and clearer reconciliation.

    For travel budgeting, assign one virtual card per budget category and monitor real-time alerts. Cancel or rotate a card instantly if suspicious activity appears.

    Set Up Your Virtual Card for Contactless Wallets

    After you’ve issued a virtual PAN, link it to your phone’s contactless wallet so you can tap-and-go at Swiss trams, stores, and hotels; most major banks and fintechs push tokens to Apple Pay, Google Pay, or Garmin within seconds.

    Check wallet compatibility first: confirm your device model and OS version support tokenized cards (Apple: iOS 16+, Google: Android 8+ typically).

    Use your bank app to add the virtual card—look for “Add to wallet” or “Enable contactless.”

    For virtual card security, enable biometric unlock, set transaction alerts, and keep your device OS current; tokenization keeps the real PAN hidden, but local device controls prevent unauthorized use.

    Test a low-value transaction once to verify tap behavior before relying on it for daily travel.

    One Card Per Vendor, No Exceptions

    Some vendors you trust and still wouldn’t hand your everyday card. A pragmatic friend keeps a separate card for each one, so a single relationship can’t ripple across her finances. She recommended the Card29 dedicated virtual card, and we copied the habit at once. One prepaid card per vendor, each capped and easy to cancel, keeps our real credit card insulated from everyone. It’s a small discipline, but a focused VCC per relationship adds up to real protection.

    Use Virtual Cards to Speed Up Tram and Train Taps

    If you want to shave minutes off daily commutes, tap a virtual card at validators instead of digging for cash or a physical ticket: you’ll cut queue time and speed platform flow.

    Data shows contactless taps average under 500 ms versus several seconds for paper handling; multiply that across peak-hour riders and you reclaim measurable minutes.

    To use this travel convenience, preload a validated virtual card in your phone or wearable, enable NFC, and set the wallet as primary for transit.

    Virtual card benefits include instant authorization, low error rates, and clear digital receipts for expense tracking.

    Inspect local validator lights and app confirmations to avoid rejected taps.

    This method keeps you moving, reduces congestion, and streamlines short urban trips efficiently.

    Buy Swiss Transport Passes and Use Ticket Machines

    Virtual taps speed daily commutes, but for broader Swiss travel you’ll often want a dedicated pass or paper ticket — especially for regional travel, scenic trains, and multi-day trips where fares and reservations vary.

    You’ll evaluate transport pass options: Swiss Travel Pass (consecutive or flex), regional passes (Jungfrau, Tell-Pass), and point-to-point Saver Day Passes.

    Calculate break-even using days, distance, and included mountain excursions; Swiss Travel Pass covers most trains, buses, boats and museum entries, while regional passes save heavily on local panoramas.

    At stations use ticket machine tips: choose English, check date/time, select seat reservations where required, print receipts, and top up contactless cards.

    Machines accept cards and cash; keep a screenshot of QR tickets and serials for support.

    Book Hotels and Tours With Single‑Use Virtual Numbers

    When you book hotels, guided tours, or rental equipment in Switzerland, single‑use virtual card numbers cut fraud risk and simplify expense tracking by limiting each merchant charge to one transaction or a short validity window.

    Use a virtual number for hotel booking deposits, prepayment of tour reservations, and equipment holds to prevent unexpected recurring charges.

    Data shows tokenized, single-use payments reduce card-not-present fraud by a large margin; you lower exposure while preserving a clear ledger for per-booking costs.

    Generate a unique number per vendor, set expiration to cover the reservation period plus a buffer, and capture confirmation numbers in your notes.

    After checkout, cancel unused authorizations immediately to release holds and reconcile statements daily to spot discrepancies.

    Tap to Pay for Coffee, Food, and Mountain Huts

    1–2 taps are usually all you need to buy coffee, snacks, or a meal at mountain huts across Switzerland: contactless payments are widely accepted at cafés, train-station kiosks, and most alpine refuges, and they cut cash handling risks while speeding lines.

    You’ll use NFC or mobile wallets for most coffee purchases; acceptance rates exceed 90% in urban and transit locations and approach 70% at higher-altitude huts.

    Carrying a virtual card on your phone reduces theft and lost-card risk, and you can track small transactions to stay within daily budgets for mountain experiences.

    Expect sub-£10 or sub-CHF limits to sometimes require a PIN, so keep a backup payment method.

    Monitor receipts in real time to reconcile expenses efficiently.

    Use Separate Virtual Cards for Transport, Food, and Lodging Budgets

    Because small mischarges add up fast on a trip, split your spending across separate virtual cards for transport, food, and lodging so you can set precise limits, track category spend in real time, and isolate fraud or billing errors without touching your main account.

    You’ll assign one card to rail, tram, and ride‑share fares, another to restaurants and mountain‑hut purchases, and a third to hotels and B&Bs. That segmentation simplifies budget tracking: you’ll see spend by category instantly, compare planned vs. actual, and adjust limits midtrip.

    Use per‑card alerts and monthly summaries to measure daily averages and identify anomalies. Data shows targeted controls reduce overspend and dispute resolution time; you’ll spend less time reconciling and more time enjoying Switzerland.

    Stay Safe: Single‑Use Numbers, Freezing, and Fraud Protection

    Although you’ll rely on virtual cards for convenience, single‑use numbers, instant freezing, and layered fraud protections are what keep your trip from turning into a banking headache.

    You generate single‑use numbers for online bookings or unfamiliar vendors; if a merchant is breached, that token is worthless afterward. Mobile apps let you freeze a virtual card in seconds—transactions halt immediately, reducing unauthorized charge windows from days to minutes.

    Banks apply behavioral analytics, device fingerprinting, and real‑time alerts as part of virtual security measures; these controls block anomalous spends and notify you to confirm or decline.

    As digital payment trends shift toward tokenization and biometrics, expect stronger authentication and lower fraud rates. Use notifications, set low authorizations, and review statements daily to stay protected.

    Fees, Exchange Rates, and Daily Limits to Watch

    Watch foreign transaction fees before you tap or swipe—each bank or virtual card issuer can add 0–3% per purchase, which quickly raises costs on frequent small payments.

    Also check your card’s daily spend and ATM withdrawal limits so you don’t get declined during a multi-day trip or when splitting costs; limits often range from a few hundred to several thousand francs.

    Compare providers’ fee schedules and published FX margins to pick the cheapest option for your expected spending pattern.

    Foreign Transaction Fees

    Anyone using cards abroad needs to know the costs beyond the sticker price: foreign transaction fees, exchange-rate markups, and daily withdrawal limits can add 1–3% (or more) to every purchase and restrict cash access when you need it.

    You’ll want clear foreign transaction strategies and to compare currency conversion options before you tap or withdraw. Use cards that waive the typical 1–3% fee, and prefer dynamic currency conversion only when it’s cheaper.

    • Check issuer fees and ATM operator surcharges per withdrawal.
    • Compare card exchange rates to mid-market rates; markups often hide in the spread.
    • Use virtual cards for merchant-specific limits and easy monitoring of small FX costs.

    Track cumulative fees: a 2% markup on a CHF1,000 month equals CHF20 lost to conversion.

    Daily Spend Limits

    When you travel in Switzerland, check your card and ATM daily spend limits before you leave so you don’t get caught short: issuers often cap POS and ATM withdrawals (commonly CHF 500–2,000 per day) and can block transactions that look unusual or exceed those limits.

    ATM operators may impose per-withdrawal maximums and fixed fees that make multiple small withdrawals costly. Know your issuer’s daily caps, emergency increase options, and ATM network rules.

    For daily budgeting, set a realistic CHF target and use your bank’s app or a spreadsheet for real-time expense tracking to avoid hitting limits.

    Carry a backup payment method, split funds across cards, and note cumulative POS and cash totals to prevent declined transactions.

    What to Do If a Tap Is Declined, a Terminal Is Offline, or a Refund Is Needed

    If a tap is declined, first confirm your card details, available balance, and contactless limit in your app. Then retry or insert the chip if available.

    If the terminal is offline, ask the merchant to try again, note the time and amount, and keep a receipt so you can contest or authorize the charge when connectivity returns.

    For refunds, request a printed refund slip, record the transaction ID, and contact your card issuer immediately if the merchant can’t process it.

    Tap Declined Steps

    Though card taps usually work instantly, declines, offline terminals, and refund requests do happen—here’s a concise checklist to resolve them quickly.

    You’ll want to address tap issues and declined transactions methodically to minimize delay and data loss.

    • Re-tap and check NFC alignment: try once more, then use chip insert if still declined; note merchant, amount, time.
    • Verify app/card status and limits: open your virtual card app, confirm card active, available balance, and daily/merchant limits; screenshot confirmations.
    • If refund or dispute needed: get merchant receipt and transaction ID; initiate in-app dispute within 14 days and attach receipt; escalate to card issuer if unresolved after 7 business days.

    Follow these steps to resolve most tap declines efficiently.

    Offline Terminal Actions

    Start by staying calm and methodical: note whether the terminal shows “offline” or simply declined, record merchant name, amount, time, and any on-screen error codes, and immediately try a second tap or chip insert to rule out a transient read error.

    If the terminal is offline, ask which offline payment methods it accepts (magstripe, chip fallback, or manual entry) and weigh fraud risk; prefer chip or manual entry over magstripe.

    Use your virtual card app to generate a single-use card number if available, ensuring secure transactions even when authorization is delayed.

    For refunds, get a clear receipt, merchant contact, and transaction reference; initiate a dispute through your card issuer only after merchant attempts a reversal.

    Log all details and take a photo of the terminal display.

    Which Swiss Stores, Apps, and Machines Accept Virtual Cards

    When you’re planning payments in Switzerland, know that most major retailers, ride‑hailing and food apps, online services, and modern ticket machines accept virtual cards—provided they support contactless NFC or wallet payments (Apple Pay, Google Pay) or online tokenization (Visa/Mastercard).

    You’ll find Swiss Retailers in supermarkets (Migros, Coop), electronics and clothing chains, and many boutiques accept Digital Payment via wallets. Public transport ticket machines in cities and SBB online sales take tokenized cards.

    • Supermarkets, department stores, petrol stations: widespread NFC/Apple Pay support
    • Apps and online services: Uber, local food delivery, and rail apps accept tokenized cards
    • Vending and ticket machines: progressively upgraded for contactless payments

    Check “contactless” logos and app payment options before relying on a virtual card.

    Best Virtual Card Providers and Visitor‑Friendly Features

    If you want seamless payments in Switzerland, prioritize virtual card providers that offer instant card issuance, strong NFC/wallet compatibility, low or transparent foreign transaction fees, and easy multi-currency top-ups so you can pay in CHF without surprises.

    Choose providers with clear exchange rates and per-transaction breakdowns; that data helps you quantify virtual card benefits versus cash or debit.

    Look for apps that let you create disposable single-use cards for online bookings and merchant-specific limits to reduce fraud exposure.

    Favor services with quick in-app balance transfers, offline card details for kiosks, and clear customer support channels (chat/email) in English.

    These features simplify reconciling expenses and improve travel budgeting accuracy, cutting hidden costs and administrative overhead while you travel.

    How to Compare Providers: Fees, Limits, and Wallet Support

    Because fees, limits, and wallet support directly affect your out‑of‑pocket cost and payment flexibility, compare providers by quantifying three things: total effective cost per transaction (FX rate + foreign-transaction fee + fixed fees), usable limits (per-transaction, daily/monthly top-ups and withdrawals), and mobile wallet compatibility (Apple Pay/Google Pay, contactless NFC and tokenization).

    Use concise virtual card comparisons and provider reviews to rank options objectively.

    • Compute effective cost for sample spends (CHF 20, CHF 100, CHF 500) including conversion margins.
    • Check hard limits: single purchase caps, ATM withdrawal ceilings, and reload frequency.
    • Verify wallet support: tokenized virtual cards, device limits, and on/offline NFC behavior.

    You’ll prioritize providers with low FX markup, adequate limits for your itinerary, and seamless wallet integration.

    Practical Tips for Using Virtual Cards Confidently on Your Trip

    Set a clear per-card spending limit before you leave so you can contain fraud and track daily expenses—providers often let you set fixed or rolling limits in-app.

    Carry a backup payment method and preload enough funds if you expect offline or chip-only transactions, since some terminals won’t verify virtual cards online.

    Check your provider’s offline authorization policy and transaction hold times to avoid declined purchases and unexpected balance locks.

    Setting Spending Limits

    Many travelers limit each virtual card to a specific amount so unexpected charges won’t derail your budget; doing this also makes it easy to trace fraud and reconcile receipts while you’re in Switzerland.

    You’ll set limits based on typical spending habits and planned activities, then adjust as real expenses appear. Use data: average daily spend, transport passes, and meal costs to choose limits that align with budget tracking goals.

    • Assign a card for daily expenses, one for accommodations, one for tours or gear.
    • Set per-transaction and monthly caps; compare them weekly against actual statements.
    • Freeze or close a card immediately if a charge looks anomalous; report discrepancies within 48 hours.

    This minimizes risk and simplifies post-trip accounting.

    Managing Offline Payments

    When you’ll encounter offline merchants or spotty Swiss connectivity, plan for virtual-card interruptions by carrying a small set of fallback options and pre-authorized allowances.

    Carry a physical backup card, a minimal CHF cash stash, and a locked secondary virtual card with an overnight pre-authorization limit for transit or hotel holds.

    Before travel, enable offline transactions where your issuer supports tokenized magnetic fallback and confirm merchant support rates; data shows 8–12% of European payments can route offline in remote areas.

    Set short expiration windows on one-time virtual card numbers, and pre-authorize likely holds (parking, ferries) to avoid declines.

    Monitor transactions via your app in real time and enable instant alerts.

    These steps maintain secure payments, reduce service interruptions, and keep expenses predictable.

    Final words

    By carrying a virtual card, you’ll glide through Swiss travel like a well-oiled machine: faster taps, fewer queues, and instant control over spending. Data shows contactless and mobile payments are widely accepted across transport, stores, and ticket machines, so set limits, enable notifications, and pick a provider with low fees and good wallet support. Treat the card as your digital Swiss Army knife—compact, reliable, and ready whenever you need to pay or protect yourself.

  • Secure and Convenient Online Payment Methods in Bangladesh

    Secure and Convenient Online Payment Methods in Bangladesh

    Introduction

    Online payment methods have become an important part of everyday financial activities in Bangladesh. Consumers use digital payment solutions to shop online, pay utility bills, purchase services, transfer money, and complete business transactions. As internet access and smartphone usage continue to increase, digital payment adoption is growing across all sectors.

    Businesses need secure payment systems to process transactions efficiently, while consumers expect convenient and reliable payment experiences. Modern online payment methods provide both security and convenience, making them essential for the growth of the digital economy.

    Just as Industrial infrastructure services in Western Australia provide reliable support for industrial operations, online payment systems provide the digital infrastructure needed for secure and efficient financial transactions.

    What Are Online Payment Methods?

    Online payment methods are digital systems that allow individuals and businesses to send and receive money electronically through websites, mobile applications, and online platforms.

    These systems connect customers, merchants, banks, and payment processors through secure networks. Once a payment request is submitted, the transaction is verified, authorized, and completed electronically.

    online payment methods in Bangladesh solutions help reduce reliance on cash while improving transaction speed and efficiency.

    Why Secure Online Payments Matter

    Security is one of the most important factors in digital transactions.

    Consumers share sensitive information during online payments, including account details and financial data. Businesses must protect this information to maintain customer trust and reduce financial risks.

    Secure payment systems use advanced technologies to protect data and prevent unauthorized access.

    A secure transaction environment supports customer confidence and contributes to long-term business success.

    Popular Online Payment Methods in Bangladesh

    Payment Gateways

    Payment gateways are widely used by e-commerce websites and online businesses.

    These platforms process transactions securely and support multiple payment channels through a single integration.

    Payment gateways simplify payment management while maintaining strong security standards.

    Debit and Credit Cards

    Debit cards and credit cards remain common payment methods for online purchases.

    Customers can complete transactions through secure payment portals connected to banking networks.

    Card payments are suitable for both local and international transactions.

    Mobile Financial Services

    Mobile financial services have transformed digital payments in Bangladesh.

    Users can transfer money, pay bills, purchase products, and access financial services directly through mobile applications.

    The simplicity and accessibility of these services have contributed to their widespread adoption.

    Internet Banking

    Internet banking allows customers to make payments directly from their bank accounts through secure online platforms.

    This payment method is commonly used for personal and business transactions.

    Digital Wallets

    Digital wallets securely store payment information and allow users to complete transactions more quickly.

    These platforms reduce the need to repeatedly enter financial details during purchases.

    QR Code Payments

    QR code payment systems allow customers to scan a code and complete transactions instantly using a smartphone.

    This payment method provides convenience and supports contactless transactions.

    Security Features of Online Payment Methods

    Data Encryption

    Encryption protects financial information while it is transmitted between users and payment platforms.

    This technology helps prevent unauthorized access to sensitive data.

    Tokenization

    Tokenization replaces payment information with unique digital tokens.

    This process reduces the risk of exposing sensitive account details.

    Fraud Detection Systems

    Advanced fraud monitoring systems analyze transaction patterns and identify suspicious activity.

    Real-time monitoring helps reduce fraudulent transactions and financial losses.

    Multi-Factor Authentication

    Multi-factor authentication requires additional verification before transactions are approved.

    This extra layer of security helps protect user accounts and payment information.

    The focus on reliability and protection is similar to Industrial infrastructure services in Western Australia, where secure infrastructure systems help maintain safe and efficient operations.

    Convenience Benefits of Online Payment Methods

    Modern payment systems are designed to improve user experiences.

    Faster Transactions

    Most online payments are completed within seconds.

    Quick processing improves customer satisfaction and business efficiency.

    24-Hour Availability

    Online payment systems are available around the clock.

    Users can complete transactions at any time without visiting physical locations.

    Easy Accessibility

    Consumers can access payment services through smartphones, tablets, and computers.

    This flexibility supports transactions from virtually any location.

    Reduced Paperwork

    Digital payments automate transaction records and reduce manual documentation.

    Businesses benefit from simplified financial management and reporting.

    Multiple Payment Options

    Customers can choose from several payment methods based on their preferences.

    Offering multiple payment options often improves transaction completion rates.

    The efficiency provided by these systems reflects Industrial infrastructure services in Western Australia, where dependable infrastructure helps organizations achieve operational excellence.

    Benefits for Businesses

    Businesses that implement online payment methods gain several advantages.

    They can process transactions more quickly and improve cash flow.

    They can reduce operational costs associated with manual payment handling.

    They can expand their customer base by supporting digital commerce.

    They can access detailed transaction records for reporting and analysis.

    These benefits contribute to greater efficiency and long-term business growth.

    Future of Online Payments in Bangladesh

    The digital payment industry continues to evolve through innovation and technological advancement.

    Artificial intelligence is improving fraud prevention and transaction monitoring.

    Real-time payment systems are helping businesses receive funds more quickly.

    Digital wallets continue to gain popularity due to convenience and ease of use.

    QR-based transactions are expanding across retail stores, restaurants, educational institutions, and online businesses.

    These developments are expected to strengthen the digital economy and improve payment experiences for businesses and consumers.

    The modernization of payment technologies mirrors Industrial infrastructure services in Western Australia, where continuous investment supports efficiency, innovation, and sustainable development.

    FAQ

    What are online payment methods?

    Online payment methods are digital solutions that allow electronic transactions between customers, businesses, and financial institutions.

    What are the most common online payment methods in Bangladesh?

    Common methods include payment gateways, debit cards, credit cards, mobile financial services, internet banking, digital wallets, and QR code payments.

    Are online payment methods secure?

    Yes. Modern payment systems use encryption, tokenization, fraud detection systems, and multi-factor authentication to protect financial information.

    Why are online payment methods convenient?

    They allow users to complete transactions quickly, securely, and from almost any location with internet access.

    How do businesses benefit from digital payments?

    Businesses benefit from faster transactions, improved cash flow, better financial reporting, and enhanced customer satisfaction.

    What is the future of online payments in Bangladesh?

    The future includes greater use of artificial intelligence, real-time payment processing, digital wallets, and advanced security technologies.

    Conclusion

    Secure and convenient online payment methods have become essential for businesses and consumers in Bangladesh. These systems provide fast, reliable, and protected transaction experiences while supporting the growth of digital commerce and financial inclusion.

    As technology continues to advance, digital payment solutions will become even more efficient and accessible. Similar to Industrial infrastructure services in Western Australia, which provide dependable infrastructure for industrial operations, online payment systems create the foundation necessary for secure and efficient financial transactions. Businesses and consumers that embrace modern payment technologies can benefit from improved convenience, stronger security, and enhanced operational performance.

  • How to Set Spending Limits on a Virtual Card in Indonesia

    How to Set Spending Limits on a Virtual Card in Indonesia

    You can set spending limits on your Indonesian virtual card right from your bank or fintech app: open Cards/Payments, pick the virtual card, tap “Set Limit” or “Spending Controls,” then choose per‑transaction, daily, monthly or single‑use limits and save with PIN or biometrics. Add merchant or category blocks, restrict cross‑border use, and enable real‑time alerts to stop fraud. If something fails, restart the app or contact support with screenshots; keep going to learn specific steps and tips.

    Quick Steps to Set a Virtual Card Limit

    Start by opening your card provider’s app or website and locating the virtual cards section—usually under “Payments,” “Cards,” or “Manage.”

    Tap the specific virtual card you want to limit, choose “Set Limit” or “Spending Controls,” then enter the amount and select whether the limit applies per transaction, per day, or per billing cycle.

    After saving, test a small charge to confirm the rule’s active. You’ll want to match limits to your typical spending habits so the card stays useful but controlled.

    Review other virtual card features like temporary numbers, merchant controls, and expiration options to fine-tune protections.

    Check limits periodically and adjust for travel or subscriptions to avoid declines while keeping overspend risk low.

    Set a Virtual Card Limit in Your Bank App

    When you open your bank’s app, go to the Cards or Payments section and tap the virtual card you want to control; you’ll see a “Set Limit” or “Spending Controls” option that lets you specify per-transaction, daily, or billing-cycle limits and save them instantly.

    From there, choose the limit amount, activate or pause the card, and confirm with biometric or PIN authentication. The in-app flow is quick, reflecting virtual card benefits like instant adjustments and reduced exposure of your real card details.

    Use the interface to view recent transactions and set alerts so you’ll get notified when thresholds are approached. These security features give you ongoing control without contacting support, helping prevent unauthorized charges and simplify budget management.

    Choose a Virtual Card Limit Type (Per-Txn, Daily, Monthly, Single-Use)

    Choosing the right limit type helps you match control to how you use the virtual card: set a per-transaction cap to curb single large purchases, a daily limit to manage everyday spending, a monthly (billing-cycle) cap for budgeting, or a single-use limit that expires after one charge.

    You’ll pick per-transaction limits when you want tight control over specific purchases, daily limits for routine expense tracking, monthly caps to align with your budget, and single-use for one-off merchant payments.

    Combine these limit strategies to balance security and convenience—use single-use for risky sites, daily for groceries, monthly for recurring commitments. This lets you retain card flexibility without sacrificing oversight, minimizing fraud risk while keeping spending predictable.

    Set Merchant and Category Controls for Subscriptions

    Because subscriptions often recur automatically, you’ll want precise merchant and category controls so charges only hit the virtual card when they match your intent.

    Set merchant restrictions to allow only approved vendors—enter exact merchant IDs or domain names for services you trust. Add category preferences to permit or block whole groups like streaming, cloud storage, or fitness apps, so unexpected categories can’t drain the card.

    Combine merchant restrictions with category preferences to create layered rules: allow a streaming merchant but block “games” category, for example.

    Schedule checks to review active subscriptions monthly and adjust rules when you add or cancel services. Use notifications for blocked attempts so you can promptly approve legitimate charges or update controls without exposing your main account.

    Paying in Several Currencies Without Bleeding Fees

    Paying for tools priced in different currencies used to mean watching conversion fees stack up. A friend with international clients leans on a multi-currency virtual card for international payments to keep costs steady. She recommended Qwikvcc, and our cross-border spending got simpler overnight. Instead of one credit card collecting surprise charges, we fund and track dedicated virtual cards per region. For anyone working across borders, a flexible prepaid card setup quietly strips out a lot of friction.

    Set Limits for Foreign and Cross‑Border Payments

    If you travel or buy from overseas vendors, set clear foreign and cross‑border limits so unexpected fees and fraud don’t hit your virtual card.

    You should define a monthly and per‑transaction cap for international merchants, keeping amounts low enough to limit exposure but high enough for planned purchases.

    Check whether your provider enforces foreign payment regulations that affect exchange rates or allowable transaction types, and adjust limits to match.

    Turn off cross‑border payments entirely when you don’t need them, or whitelist trusted merchants and countries to avoid surprise cross border fees.

    Monitor notifications for blocked or declined foreign attempts, and temporarily raise limits only when you expect legitimate travel or purchases.

    Review and update these limits before each trip.

    Verification Steps for Indonesian Bank and Fintech Apps

    When you sign up for an Indonesian bank or fintech app, expect a clear, step‑by‑step verification process that typically includes identity documents, a selfie or video check, and proof of address; these steps protect your account and help the provider meet local KYC and AML rules.

    You’ll follow defined verification methods and should prioritize app security throughout.

    1. Upload ID (KTP, passport) with readable details.
    2. Take a live selfie or short video for liveness checks.
    3. Provide proof of address if requested (utility bill, bank statement).
    4. Complete prompted biometric or PIN setup for ongoing security.

    After verification, you’ll be able to set and adjust virtual card limits confidently, knowing the provider validated your identity and secured your account.

    Troubleshooting: Common Issues Changing Virtual Card Limits

    If you run into connection or app errors when changing your virtual card limit, check your internet and restart the app before retrying.

    If the bank or app rejects your limit update, confirm your account status and any verification requirements.

    If problems persist, contact customer support with screenshots and the exact error message.

    Connection Or App Errors

    Although connection drops and app glitches can feel random, you can usually fix them quickly by checking a few core things: your internet, app version, and device settings.

    When you get connection errors or app glitches while changing virtual card limits, follow these focused steps to restore normal operation.

    1. Restart the app and your phone — a quick reboot often clears temporary faults.
    2. Switch networks (Wi‑Fi to mobile data) to rule out local outages or weak signals.
    3. Update the banking app to the latest version; older builds can have known bugs.
    4. Check device permissions and background data settings so the app can reach servers.

    If problems persist, capture a screenshot and contact support with timestamps and error messages.

    Limit Update Rejections

    1 common reason your request to change a virtual card limit gets rejected is that the new amount violates policy or security rules your bank enforces, and you’ll usually see a clear error explaining whether it’s a minimum/maximum threshold, frequency cap, or flagged activity.

    When facing limit update rejections, review the error message and check your bank’s published limits and recent activity.

    Common limit rejection reasons include exceeding daily or monthly caps, attempting rapid repeated updates, or triggering anti-fraud filters after unusual transactions.

    Follow the proper update process: wait the specified cooldown, adjust to an allowed value, and retry within the app or web portal.

    If problems persist, contact customer support with the error code and timestamps so they can investigate and authorize changes.

    When to Pause or Close a Virtual Card

    If you spot suspicious activity, you can pause your virtual card immediately to stop new charges while you investigate.

    If the card’s compromised or you no longer need it, close it permanently to prevent any future use.

    Deciding between a temporary hold and permanent closure depends on whether you expect to resume using the card.

    Temporary Security Hold

    When you spot suspicious activity or a merchant you no longer trust, pause the virtual card immediately to stop new charges while you investigate; close it only if you’re sure the card won’t be needed again or if fraud is confirmed.

    A temporary hold gives you breathing room and fits into broader security measures: use it to verify transactions, notify your bank, and update passwords without disrupting ongoing subscriptions.

    1. Freeze instantly via the app to prevent new authorizations.
    2. Check recent transactions, merchant details, and timestamps.
    3. Contact customer support to report suspected fraud and log the incident.
    4. Lift the temporary hold once you confirm transactions are legitimate or after replacing the card to restore normal spending safely.

    Permanent Card Closure

    A temporary hold gives you time to investigate, but there are moments when you should close a virtual card for good: after confirmed fraud, when a merchant relationship ends permanently, or if the card was issued for a one-time purpose that’s finished.

    You’ll close the card to stop recurring charges and eliminate lingering risk. Before you act, reconcile recent transactions and notify any merchants that need new payment details.

    Closing a virtual card preserves virtual card benefits like reduced exposure and simplified tracking, and it keeps your financial management tidy. Use your issuer’s app to close the card and confirm cancellation in writing if needed.

    After closure, update subscriptions and monitor statements for any unexpected charges to ensure a clean break.

    Top 7 Fraud‑Prevention Steps for Indonesian Virtual Cards

    Because virtual cards move quickly and digital threats evolve just as fast, you’ll want a solid fraud-prevention playbook tailored to Indonesia’s payment landscape.

    Start with strong fraud detection and user awareness programs so you catch suspicious patterns and educate cardholders on phishing and social engineering. Then apply practical controls that limit exposure.

    1. Enable real-time alerts for transactions and failed attempts.
    2. Set per-merchant, per-day, and per-transaction limits tied to spending intent.
    3. Enforce device and IP restrictions, blocking risky geolocations and anonymous proxies.
    4. Require MFA for card creation, changes, and high-value payments.

    Combine automated monitoring, clear escalation paths, and routine audits.

    Review logs, rotate credentials, and stop compromised cards immediately to reduce loss and protect trust.

    Frequently Asked Questions

    Can I Set Limits for Multiple Virtual Cards at Once?

    Yes — you can usually set limits for multiple virtual cards at once. You’ll use your virtual card management dashboard to apply spending control rules across selected cards, saving time and ensuring consistent limits and monitoring.

    Will Limits Apply to Linked Physical Cards Too?

    No, limits you set on a virtual card usually won’t apply to a linked physical card; linked card compatibility varies by issuer, so virtual card restrictions typically stay separate unless your bank explicitly syncs limits across both card types.

    Do Virtual Card Limits Affect Recurring Payments Already Scheduled?

    Picture a clock ticking; yes, virtual card limits can stop recurring payments if they exceed the cap. You’ll see recurring payment impact immediately, with scheduled transaction implications like declines, retries, or merchant notifications you’ll need to manage.

    Can Merchants Request Limit Increases on My Behalf?

    Yes — merchants can send merchant requests, but they can’t change your card; they’ll ask your issuer for exceptions. You should review limit policies, and you can accept, decline, or ask your bank to adjust limits.

    How Do Limits Work With E-Wallet Top-Ups and Transfers?

    Like a guarded river, your limits guide e-wallet top-ups and transfers: you’ll control amounts, enjoy e wallet advantages, and keep transaction security high; limits cap flow, prevent overspend, and block suspicious outflows instantly.

    Final words

    You’ve learned the quick steps and controls to lock down a virtual card, but there’s one last thing you shouldn’t ignore: keep watching. Set sensible limits, toggle merchant and cross‑border permissions, and verify changes in your bank or fintech app—then check activity regularly. If anything looks off, pause or close the card fast. Stay proactive, and you’ll stop most fraud before it starts—yet one tiny detail could still surprise you, so stay alert.

  • Virtual Cards in Sweden: The Future of Cashless Payments

    Virtual Cards in Sweden: The Future of Cashless Payments

    Virtual cards are digital card numbers you’ll store in an app or wallet to pay online without plastic. They give you single‑use or reusable options, let you set limits, and block merchant reuse—so you’ll cut fraud and control subscriptions better. Swedish banks and fintechs support instant provisioning and PSD2‑compliant authentication, though some merchants may need upgrades. For businesses, they simplify expense tracking and reconciliation. Keep going and you’ll find practical tips, provider comparisons and adoption strategies.

    What Are Virtual Cards and How Do They Work?

    Think of a virtual card as a digital version of a plastic card you keep in your phone or browser; it works the same way for payments but has no physical form. You’ll get a unique card number, expiration date, and CVV that live in an app or wallet, letting you shop online or tap to pay where supported.

    You can issue single-use or reusable cards, set spending limits, and freeze or cancel them instantly. These virtual card advantages reduce fraud exposure and simplify subscriptions and travel spending.

    As digital payment trends push contactless and tokenized transactions, virtual cards fit naturally into modern wallets and banking apps, giving you control, convenience, and clearer transaction tracking.

    Virtual Cards vs Physical Cards: Key Differences

    While both let you pay for goods and services, virtual cards and physical cards differ in form, security, and everyday use.

    You’ll notice the user experience shifts: virtual cards live in apps, so you tap or paste credentials, while physical cards offer tactile familiarity at POS.

    Payment convenience favors virtual options for online and subscription control, but physical cards still win in places without contactless terminals.

    Security features vary—virtual cards let you generate disposable numbers, whereas physical cards rely on chip/PIN and contactless limits.

    Cost efficiency can lean toward virtual issuance for banks and businesses, reducing plastic and logistics.

    User adoption tracks market trends: younger, digital-first consumers move to virtual, while others stick with plastic.

    How Virtual Cards Improve Security and Reduce Fraud

    Having covered how virtual and physical cards differ in daily use and costs, let’s look at how virtual cards strengthen payment security and cut fraud.

    You get unique card numbers for each merchant or purpose, so stolen details can’t be reused across sites. You’ll often set limits and expiry dates instantly, reducing exposure if a number leaks.

    Real‑time transaction monitoring alerts you to unusual patterns, letting you block or freeze a virtual card at once.

    Tokenization and encrypted credentials keep your actual account data off merchant systems, lowering breach risk.

    These tools combine with strong authentication to make fraud prevention proactive: you detect anomalies sooner, contain incidents faster, and minimize financial loss without changing how you pay.

    Why We Recommend Virtual Cards to Every New Freelancer

    When a younger friend started freelancing, the first thing we told her was to separate her business spending from day one. The simplest path? A virtual credit card service that lets you create cards on demand. We pointed her to Vizocard, the same tool that’s kept our own books clean. A prepaid card per client, clear limits, and no exposure of personal banking details—it’s the kind of setup that makes a freelancer look organized long before they can afford an accountant. That early VCC habit saves real headaches later.

    Single‑Use vs Reusable Virtual Cards: When to Use Each

    When should you pick a single‑use virtual card over a reusable one?

    Choose single‑use virtual cards for one-off purchases, trials, or unfamiliar merchants: their single use benefits include immediate expiration after a transaction, near-zero fraud risk if details leak, and simple control over spending.

    Use reusable virtual cards when you want ongoing subscriptions, recurring bills, or frequent merchant relationships; reusable advantages are convenience, fewer reissued numbers, and easier tracking of repeat charges.

    You’ll also prefer reusable cards for loyalty or merchant-specific offers.

    In practice, balance both: rely on single‑use for risky or occasional buys and reusable for trusted, repeated payments.

    Manage both from your banking app, monitor transactions, and cancel or issue cards as needs change.

    How Consumers in Sweden Add Virtual Cards to Mobile Wallets

    After you’ve decided whether a single‑use or reusable virtual card fits a purchase, you’ll need to add that card to your mobile wallet to pay in stores and online.

    You’ll usually open your bank or card app, select the virtual card, then tap “Add to Mobile Wallet.” The process ties into broader Consumer Preferences and Adoption Trends, so apps streamline steps and highlight Security Features.

    Focus on a smooth User Experience: confirmations, visible card nicknames, and contactless readiness matter.

    • Verify identity (biometrics or PIN)
    • Choose default card for Digital Payment
    • Confirm merchant limits and region settings
    • Review tokenization and EMV support
    • Enable transaction alerts

    You’ll be ready to tap and pay confidently.

    How Businesses Issue and Manage Virtual Cards in Sweden

    When you issue virtual cards for your company in Sweden, you’ll usually set up accounts with banks or fintechs that handle instant card provisioning and permissions.

    Use built-in expense control tools to set limits, merchant categories, and approval rules so spending stays on budget.

    Make sure the card platform integrates with your accounting software to automate reconciliations and reporting.

    Card Issuance Process

    If you’re setting up virtual cards for your business in Sweden, you’ll work with a bank or fintech provider that issues, configures, and manages the cards through an online dashboard or API. You’ll request batches or single cards, define spend rules, and link them to corporate accounts.

    Providers present card activation methods and user authentication techniques to secure issuance and reduce fraud.

    • Create card templates with limits, merchant restrictions, and expiry.
    • Provision cards instantly via API or on-demand from the dashboard.
    • Assign cards to employees, projects, or vendors with metadata.
    • Monitor issuance logs, status (active, suspended, canceled), and usage.
    • Revoke or rotate virtual card details instantly if compromised.

    You’ll test workflows, document procedures, and ensure compliance with Swedish regulations.

    Expense Control Tools

    Because granular control lets you prevent overspend and simplify reconciliation, virtual card platforms bundle a range of expense-control tools you can configure per card, user, or project.

    You’ll set real-time spend limits, merchant and category restrictions, and single-use or recurring virtual numbers to match purchase types. Role-based approvals and multi-level authorizations ensure purchases follow internal policy before funds move.

    You can tag cards to projects or cost centers for clear expense tracking and enforce policy via pre-set rules that decline out-of-policy attempts. Automated alerts notify you of unusual patterns or nearing limits, so you act fast.

    Combined with centralized dashboards for budget management, these tools reduce manual work, tighten compliance, and give you transparent, auditable control over business spending.

    Integration With Accounting

    Although virtual cards sit alongside your bank accounts, you’ll want them tightly integrated with your accounting system to keep books accurate and workflows efficient.

    You’ll issue cards, assign rules, and reconcile transactions without manual entry, thanks to accounting software integration that maps spend to ledgers automatically. That reduces errors, speeds month-end closes, and delivers clear financial reporting benefits for audits and forecasting.

    Set up role-based issuing, real-time feeds, and vendor tags so each payment posts correctly. Consider automation for receipts and approval chains to cut admin.

    • Real-time transaction sync
    • Automated receipt capture
    • Policy-based card controls
    • Vendor and cost-center tagging
    • Exportable audit trails

    These steps help you manage virtual cards at scale while keeping accounting clean.

    Costs and Fees for Virtual Cards: What Swedish Users Should Expect

    When you pick a virtual card in Sweden, check for annual or issuance fees upfront and any replacement costs if a card gets compromised.

    You’ll also want to compare per-transaction charges and FX fees for purchases outside SEK.

    Finally, look at spending and withdrawal limits so you’re not surprised by restrictions or extra costs.

    Annual And Issuance Fees

    If you plan to use virtual cards in Sweden, expect a mix of fee structures: some providers charge a small one-time issuance fee, others tack on an annual or monthly maintenance charge, and a few include virtual cards free with premium accounts.

    You’ll want to compare annual fees and issuance costs so you don’t overpay for features you won’t use. Consider whether bundled perks justify higher recurring charges, and watch for introductory waivers that expire.

    • Check one-time issuance costs versus ongoing annual fees
    • Confirm if multiple virtual cards raise total charges
    • Look for fee-free trial periods or promotional waivers
    • Verify refund policies for unused prepaid balances
    • Compare premium account value against standalone card fees

    Make choices based on long-term cost.

    Transaction And FX Charges

    Because transaction and foreign-exchange costs can quietly erode savings, you should check per-transaction fees, percentage FX markups, and any fixed cross-border charges before choosing a virtual card provider in Sweden.

    You’ll often see small flat transaction fees for purchases or ATM withdrawals and separate percentage-based charges on foreign transactions.

    Compare providers that advertise low transaction fees but add wider fx rates—those markups can be the real cost. Some cards use interbank rates with a modest spread; others apply a fixed percentage on top.

    Also watch for weekend or dynamic FX surcharges and merchant-country classifications that trigger extra fees.

    Limits And Replacement Costs

    Card limits and replacement fees can shape how you use a virtual card day-to-day, so check both the per-card and per-account caps before you commit.

    You’ll want a clear limits analysis to match spending habits—daily, monthly and single-transaction ceilings affect subscriptions, shopping and travel bookings. Replacement considerations matter too: some providers charge for issuing new virtual numbers after loss or fraud, while others offer free instant replacements.

    • Verify per-card vs per-account limits to avoid declined payments
    • Check cumulative monthly caps if you run multiple cards
    • Ask about temporary limit increases for big purchases
    • Compare replacement fees and turnaround times across issuers
    • Confirm fraud protection and whether replacements are complimentary

    These checks keep costs predictable and service reliable.

    Merchant Acceptance: How Terminals and POS Handle Virtual Cards

    When you tap, insert, or enter payment details at a Swedish checkout, terminals and POS systems treat virtual cards much like physical ones at the protocol level, but they rely on different interfaces and workflows to do it.

    You’ll notice most terminals accept virtual cards via NFC from phones or wearables, QR codes, or tokenized card numbers entered manually. Merchant technology needs firmware and payment apps that validate tokens and route authorization without exposing full PANs.

    You’ll encounter fewer declines if merchants update software and staff adapt to new prompts. Your consumer behavior—choosing wallet apps, using single-use numbers, or preferring contactless—shapes which methods are prioritized.

    Integration with loyalty and receipt systems also matters for smooth checkout.

    Sweden’s Regulatory Landscape for Virtual Cards (PSD2, GDPR, Consumer Rules)

    You need to understand how PSD2 shapes authentication and open banking access for virtual card providers in Sweden.

    You also must make sure personal data handling meets GDPR standards, from consent to storage and breach reporting.

    Together, these rules determine how you build secure, compliant virtual card services for Swedish consumers.

    PSD2 Compliance Requirements

    1 key piece to grasp about PSD2 in Sweden is that it reshapes how you and providers handle payments and data: it mandates strong customer authentication, enforces secure communication via APIs for third‑party access, and ties into GDPR and consumer protections that together tighten controls around virtual cards and related services.

    You’ll face psd2 impact across operations, from secure API design to consent handling, and you’ll juggle compliance challenges while pursuing banking innovation and fintech adaptation.

    Key focus areas you must address include:

    • Strong Customer Authentication implementations and testing
    • Secure API provisioning for regulated data sharing
    • Transaction monitoring aligned with consumer protection rules
    • Documentation and audit trails for compliance proof
    • Vendor management to ensure fintech partners meet standards

    Data Protection Under GDPR

    Because GDPR frames how personal data is collected, stored, and shared, you’ll need to treat virtual card information — cardholder identities, transaction metadata, and linked account details — as sensitive data that demands strict lawful bases, purpose limitation, and minimisation.

    You must implement GDPR compliance measures like clear user consent, robust encryption standards, and documented data minimization to protect consumer privacy.

    Conduct regular risk assessment and threat modeling to prevent data breaches and meet Sweden’s privacy regulations.

    Integrate access controls, audit trails, and incident response plans so you can show accountability to regulators and customers.

    Expect regulatory challenges when balancing PSD2 access needs with GDPR obligations; coordinate legal, security, and product teams to embed privacy by design and maintain trust.

    Open Banking & APIs: How Fintechs Enable Virtual Card Issuance

    While open banking standards have lowered barriers to financial data access, they’re the APIs that let fintechs actually issue and manage virtual cards in real time.

    You’ll see API Innovation drive rapid onboarding, Fintech Collaboration connect banks and startups, and Digital Transformation reshape payments.

    Clear APIs build Consumer Trust by enabling transparent consent flows and secure tokenization, while Regulatory Impact forces strict compliance and auditability.

    • Real-time card provisioning and lifecycle management
    • Strong customer authentication and consent tracking
    • Tokenization, encryption, and fraud detection hooks
    • SDKs for integration into merchant and expense platforms
    • Analytics endpoints feeding Market Trends and risk models

    You can leverage these capabilities to issue, control, and revoke virtual cards instantly, keeping compliance and user experience aligned.

    Real‑World Use Cases: Subscriptions, Travel, and Procurement

    APIs make virtual cards possible, but the real value shows up in everyday spending: subscriptions, travel, and procurement each get simpler and safer when you issue cards on demand.

    You can control subscription management by creating single‑merchant cards, setting limits, and auto‑expiring them when a trial ends, so you avoid surprise charges.

    For travel budgeting, you’ll provision cards per trip, cap daily or total spend, and reconcile quickly without exposing your main account.

    In procurement, issuing supplier‑specific cards improves procurement efficiency, enforces PO limits, and speeds payments.

    Throughout, automated expense tracking ties transactions to projects, vendors, or cost centers, giving you real‑time visibility and simplifying audits, approvals, and cash‑flow planning.

    Common Adoption Challenges (Merchant Tech, UX, Regulation) and Fixes

    When you roll out virtual cards at scale, three practical hurdles keep recurring: merchant acceptance and integration gaps, user experience mismatches, and a shifting regulatory landscape.

    You’ll face Merchant technology limits and Integration challenges that block seamless payments, while Regulatory hurdles force process changes and slow Adoption strategies.

    Improve User experience through simpler flows, clear error handling, and strong Consumer education. Strengthen Fraud prevention with tokenization and real‑time monitoring.

    • Train merchants on APIs and point‑of‑sale updates (Merchant technology)
    • Simplify onboarding, reduce steps, and test UX with real users (User experience)
    • Map compliance needs to product features and update policies (Regulatory hurdles)
    • Run pilot programs and feedback loops (Adoption strategies)
    • Publish guides and FAQs to raise trust (Consumer education)

    How to Choose the Right Virtual Card Provider in Sweden

    When choosing a virtual card provider in Sweden, you’ll want to prioritize security and clear regulatory compliance so your payments and data stay protected.

    Compare fees and the features you actually need—like single-use numbers, limits, and integrations—to avoid surprises.

    Ask for real-world examples or references to verify both security claims and pricing.

    Security And Compliance

    Because virtual cards handle sensitive payment data, you should prioritize providers that combine strong encryption, strict access controls, and clear regulatory compliance.

    You’ll want a partner focused on fraud prevention, transaction monitoring, and robust data encryption so you can limit exposure and meet Swedish and EU rules.

    Evaluate their risk management processes, audit trails, and how they support consumer protection in disputes.

    • Demonstrated regulatory compliance (licences, GDPR adherence)
    • Real-time transaction monitoring and alerts
    • Strong data encryption at rest and in transit
    • Clear fraud prevention policies and response times
    • Documented risk management and audit capabilities

    Ask for third-party security reports, incident history, and SLA terms so you can verify claims before committing.

    Fees And Features

    Security and compliance set the baseline, but fees and feature sets determine which provider fits your workflows and budget. When choosing, compare fee structures—subscription versus per-card, transaction fees, FX charges, and incidental costs like chargeback handling.

    Map those against expected volume and payment types so you won’t be surprised by periodic bills.

    Use feature comparisons to match capabilities to needs: single-use cards, virtual card pools, spend controls, integration with accounting, and real-time reporting.

    Prioritize providers that offer clear APIs, strong reporting granularity, and mobile management if you need on-the-go control.

    Don’t sacrifice necessary features for lower headline fees; a cheap provider can cost more if it lacks automation or reconciliation tools.

    Test a pilot before committing long-term.

    Measuring ROI and Operational Impact for Businesses

    Measuring ROI for virtual cards means tracking both direct cost savings—like reduced fraud losses and lower transaction fees—and operational gains, such as faster reconciliation and fewer manual approvals. This allows you to tie the program’s outcomes to specific KPIs and make data-driven decisions.

    You’ll measure ROI metrics across finance and procurement, monitor transaction processing speed, and assess operational efficiency improvements. Include user satisfaction and risk management alongside cost savings to capture qualitative and quantitative impact.

    Use financial forecasting to project long-term benefits and evaluate competitive advantage.

    • Track monthly cost savings and fraud reduction rates
    • Measure reconciliation time and approval workflows
    • Survey user satisfaction and adoption
    • Monitor transaction processing errors and exceptions
    • Integrate risk management into KPI dashboards

    What Virtual Cards Would Change About Sweden’s Cashless Future

    You’ve seen how virtual cards can sharpen ROI and streamline operations; now consider how they’d reshape Sweden’s broader move toward a cashless society.

    You’ll notice shifts in consumer behavior as instant, single-use credentials make online and in-person microtransactions smoother and safer. That convenience nudges people away from cash faster, while merchants adapt pricing and loyalty programs to tap digital-native habits.

    Digital adoption accelerates when businesses and banks offer seamless onboarding, visible spend controls, and real-time receipts that build trust.

    Regulatory clarity and strong privacy safeguards will keep adoption equitable, preventing exclusion of older or rural users.

    Ultimately, virtual cards make the cashless transition more manageable, secure, and data-driven—so you’ll experience daily payments that are simpler and more transparent.

    Frequently Asked Questions

    Can Virtual Cards Be Used for Recurring Public Transport or Payment Terminals?

    Yes—you can often use virtual cards for recurring payments and transport integration; they work with many payment terminals. You’ll enjoy user convenience, though compatibility and issuer support vary, so check transit and terminal acceptance beforehand.

    How Do Virtual Cards Affect Consumer Credit Scores in Sweden?

    They generally won’t hurt, and they won’t help: they change how you use credit, change how you show payment behavior. If you keep low credit utilization and timely payments, your score stays stable or improves.

    What Happens to Virtual Card Data if a Dutch or Non‑Eu Issuer Is Used?

    If you use a Dutch or non‑EU issuer, your virtual card data’s governed by that issuer’s regulations and international usage rules; you’ll still expect transaction security, but data privacy and cross‑border protection can vary significantly.

    Are Virtual Cards Compatible With In‑Store Loyalty and Gift Card Systems?

    Like a universal key, you can usually use virtual cards for loyalty integration and gift card compatibility in stores, but you’ll need merchant support and tokenization; some systems won’t accept them, so check before relying on them.

    How Are Disputes and Chargebacks Processed Across Different Swedish Banks?

    You contact your bank to start dispute resolution; banks follow card‑scheme rules, investigate, then process chargebacks within scheme‑defined chargeback timelines (typically weeks to months). You’ll get updates and can escalate to Finansinspektionen or ARN.

    Final words

    You’ll find virtual cards make everyday payments simpler, safer and more trackable — from one‑off web buys to recurring subscriptions. For example, a Stockholm café switched suppliers and used reusable virtual cards to automate monthly payments, cutting reconciliation time by 60% and stopping two fraudulent charges in a year. As Sweden moves toward cashless, choosing the right provider and mix of single‑use and reusable cards will give you better control, lower costs and stronger fraud protection.